Latest articles
Autumn Budget 2026: What does it mean for you and your business? Chancellor John Healey delivered his first Budget on 28 October 2026, promising to give households and businesses some much-needed 'breathing space' from rising costs. While the headline rates of Income Tax on earnings, National Insurance and VAT remain unchanged, several announcements could have significant implications over the coming years. The Government expects its tax measures to raise around £7 billion a year by 2031/32, with many changes taking effect from April 2027. Here's what you need to know. Income Tax and allowances The Personal Allowance remains frozen at £12,570 for 2027/28, with most Income Tax and National Insurance thresholds unchanged until 2030/31. As earnings increase, more income may therefore become subject to tax. From 6 April 2027, Income Tax rates on savings and personal rental income will increase by four percentage points to 24%, 44% and 49%. Meanwhile, the Trading Allowance and Self Assessment trading income reporting threshold will increase from £1,000 to £3,000. Changes affecting businesses and employers The National Living Wage will rise by 3.9% to £13.21 per hour from 1 April 2027. Employers should also account for associated National Insurance and pension costs when reviewing their budgets. From 6 April 2027, Income Tax on company cars, vans, fuel and medical benefits will be collected through payroll, with most other taxable benefits following in April 2028. For businesses investing in equipment, the Annual Investment Allowance remains at £1 million. However, the main Writing Down Allowance will fall from 14% to 12% in April 2027, while the relevant First Year Allowance increases from 40% to 50% from January 2027. Corporation Tax rates remain unchanged at 19% for small profits and 25% at the main rate. Business mileage: motorcycles miss out again There is some welcome news for those using their own cars or vans for business. The 55p allowance for the first 10,000 business miles is being made permanent, while the rate for additional miles increases from 25p to 35p from April 2027. Unfortunately, the motorcycle mileage allowance remains at 24p per mile. Having previously supported the Motorcycle Action Group's campaign to increase this to 45p, I'm disappointed that motorcycles have once again been overlooked. As both a motorcyclist and an accountant, I believe there's a strong case for reviewing an allowance that hasn't changed since 2002. You can read more about my support for the campaign in my earlier article . Company directors and business owners From 6 April 2027, the lifetime limit for Business Asset Disposal Relief will fall from £1 million to £500,000, although the reduced Capital Gains Tax rate remains at 18%. Anyone considering selling their business should review the potential implications before committing to a transaction. The Government is also reviewing how profits are extracted from companies, with reforms expected from April 2028. Corporation Tax rates themselves remain unchanged. Qualifying retail, hospitality and leisure businesses in England will also benefit from changes to Business Rates Relief from April 2027, including full Small Business Rates Relief for eligible properties with a rateable value of up to £18,000. Making Tax Digital and electronic invoicing From April 2027, Making Tax Digital for Income Tax will generally apply to sole traders and landlords whose combined qualifying gross trading and property income exceeded £30,000 in 2025/26. Those affected will need to maintain digital records and submit quarterly updates to HMRC. From April 2029, VAT-registered businesses will also be required to issue and receive structured electronic VAT invoices, unless exempt. Simply sending PDF invoices won't meet the new requirements, making suitable accounting software increasingly important. Savings, pensions and household costs The planned reduction to the cash ISA limit has been reversed, meaning adults can continue saving up to £20,000 annually in cash ISAs. From April 2027, most unused pension funds and pension death benefits will be included in estates for Inheritance Tax purposes, potentially affecting estate planning. On household costs, the temporary 0% VAT rate on domestic electricity will continue until 30 June 2027, while eligible households in England will receive a £100 Household Energy Payment from January 2027. What should you do now? This Budget contained plenty of smaller announcements rather than one or two headline-grabbing changes. Some provide welcome relief, while others could increase costs or create additional administrative responsibilities. Although several measures still require legislation or further guidance, there's already plenty worth considering, particularly for employers, landlords and business owners planning future investments or a sale. The important thing isn't reacting to every Budget headline, but understanding which changes affect your circumstances and planning accordingly. If you're unsure what the Budget means for you or your business, please get in touch . We can help you understand the changes and plan ahead.
HMRC cancels record number of tax penalties – could yours be challenged? HMRC cancelled a record 48,189 tax penalties during the 2025/26 tax year, with new figures suggesting that challenging a penalty can be worthwhile if you believe it's been issued incorrectly. According to recent analysis, 65% of penalties challenged by taxpayers were cancelled. Most related to automatic fines for late filing or late payment, including the familiar £100 penalty for missing the Self Assessment deadline. Why are so many penalties being overturned? The number of cancelled penalties has been rising. The 48,189 cancelled in 2025/26 represents a 4% increase on the 46,266 overturned in 2024/25, and a reported 75% increase since 2020/21, when 5,499 penalties were cancelled during the pandemic. Many of these penalties are generated automatically, meaning there isn't necessarily someone reviewing the individual circumstances before a fine is issued. That doesn't mean every penalty is wrong, of course, but it does mean there can be circumstances that haven't been properly considered. Separate figures covering HMRC's statutory reviews, which deal with more complex tax disputes, also show an increase in decisions being changed. HMRC cancelled or amended 926 substantive decisions in 2025/26, up 35% from 688 the previous year. Meanwhile, the proportion of reviews that upheld HMRC's original decision fell from 73% to 67%. When might a penalty be challenged? One case highlighted by accountancy firm Price Bailey involved a taxpayer who received £1,600 in automated late filing penalties. The taxpayer believed their return had been successfully submitted after HMRC's online system appeared to indicate that the filing was complete. Subsequent emails from HMRC were diverted into a junk folder, meaning the problem wasn't identified until the penalties had accumulated. The case eventually reached a tax tribunal, which overturned the penalties, finding that easily missed automated communications did not amount to effective notice in those circumstances. It's a useful reminder that an automatically generated penalty isn't necessarily the final word, particularly where there are questions about whether HMRC's systems or communications have contributed to the problem. Does this mean HMRC is getting it wrong? Not necessarily in every case, but the figures do highlight the importance of reviewing penalties rather than simply assuming they're correct. Andrew Park, tax investigations partner at Price Bailey, pointed out that high-volume automated penalties lack human oversight when they're first issued. He explained that HMRC's independent internal reviewers provide an important additional check, allowing individual circumstances to be considered before disputes potentially reach a tribunal. Of course, the fact that 65% of challenged penalties were cancelled doesn't mean that 65% of all penalties issued by HMRC are incorrect. It tells us about the cases taxpayers chose to challenge, rather than every penalty HMRC issued. What should you do if you receive a penalty? The first thing is not to ignore it. Check what the penalty relates to, whether the information HMRC has used is correct and whether there are circumstances that might justify an appeal. There are time limits for challenging penalties, so it's important to act promptly rather than leaving the letter sitting on your desk. Equally, it's worth remembering that a genuine missed deadline doesn't automatically mean a penalty will be cancelled. HMRC will consider the circumstances, and an appeal needs to have a reasonable basis. For me, the interesting point from these figures is that HMRC's original decision isn't always the end of the matter. Automated systems are useful for handling large volumes of work, but they don't necessarily capture every individual circumstance. If you've received an HMRC penalty and aren't sure whether it's correct, get in touch. We can look at the circumstances and help you understand whether there may be grounds to challenge it.
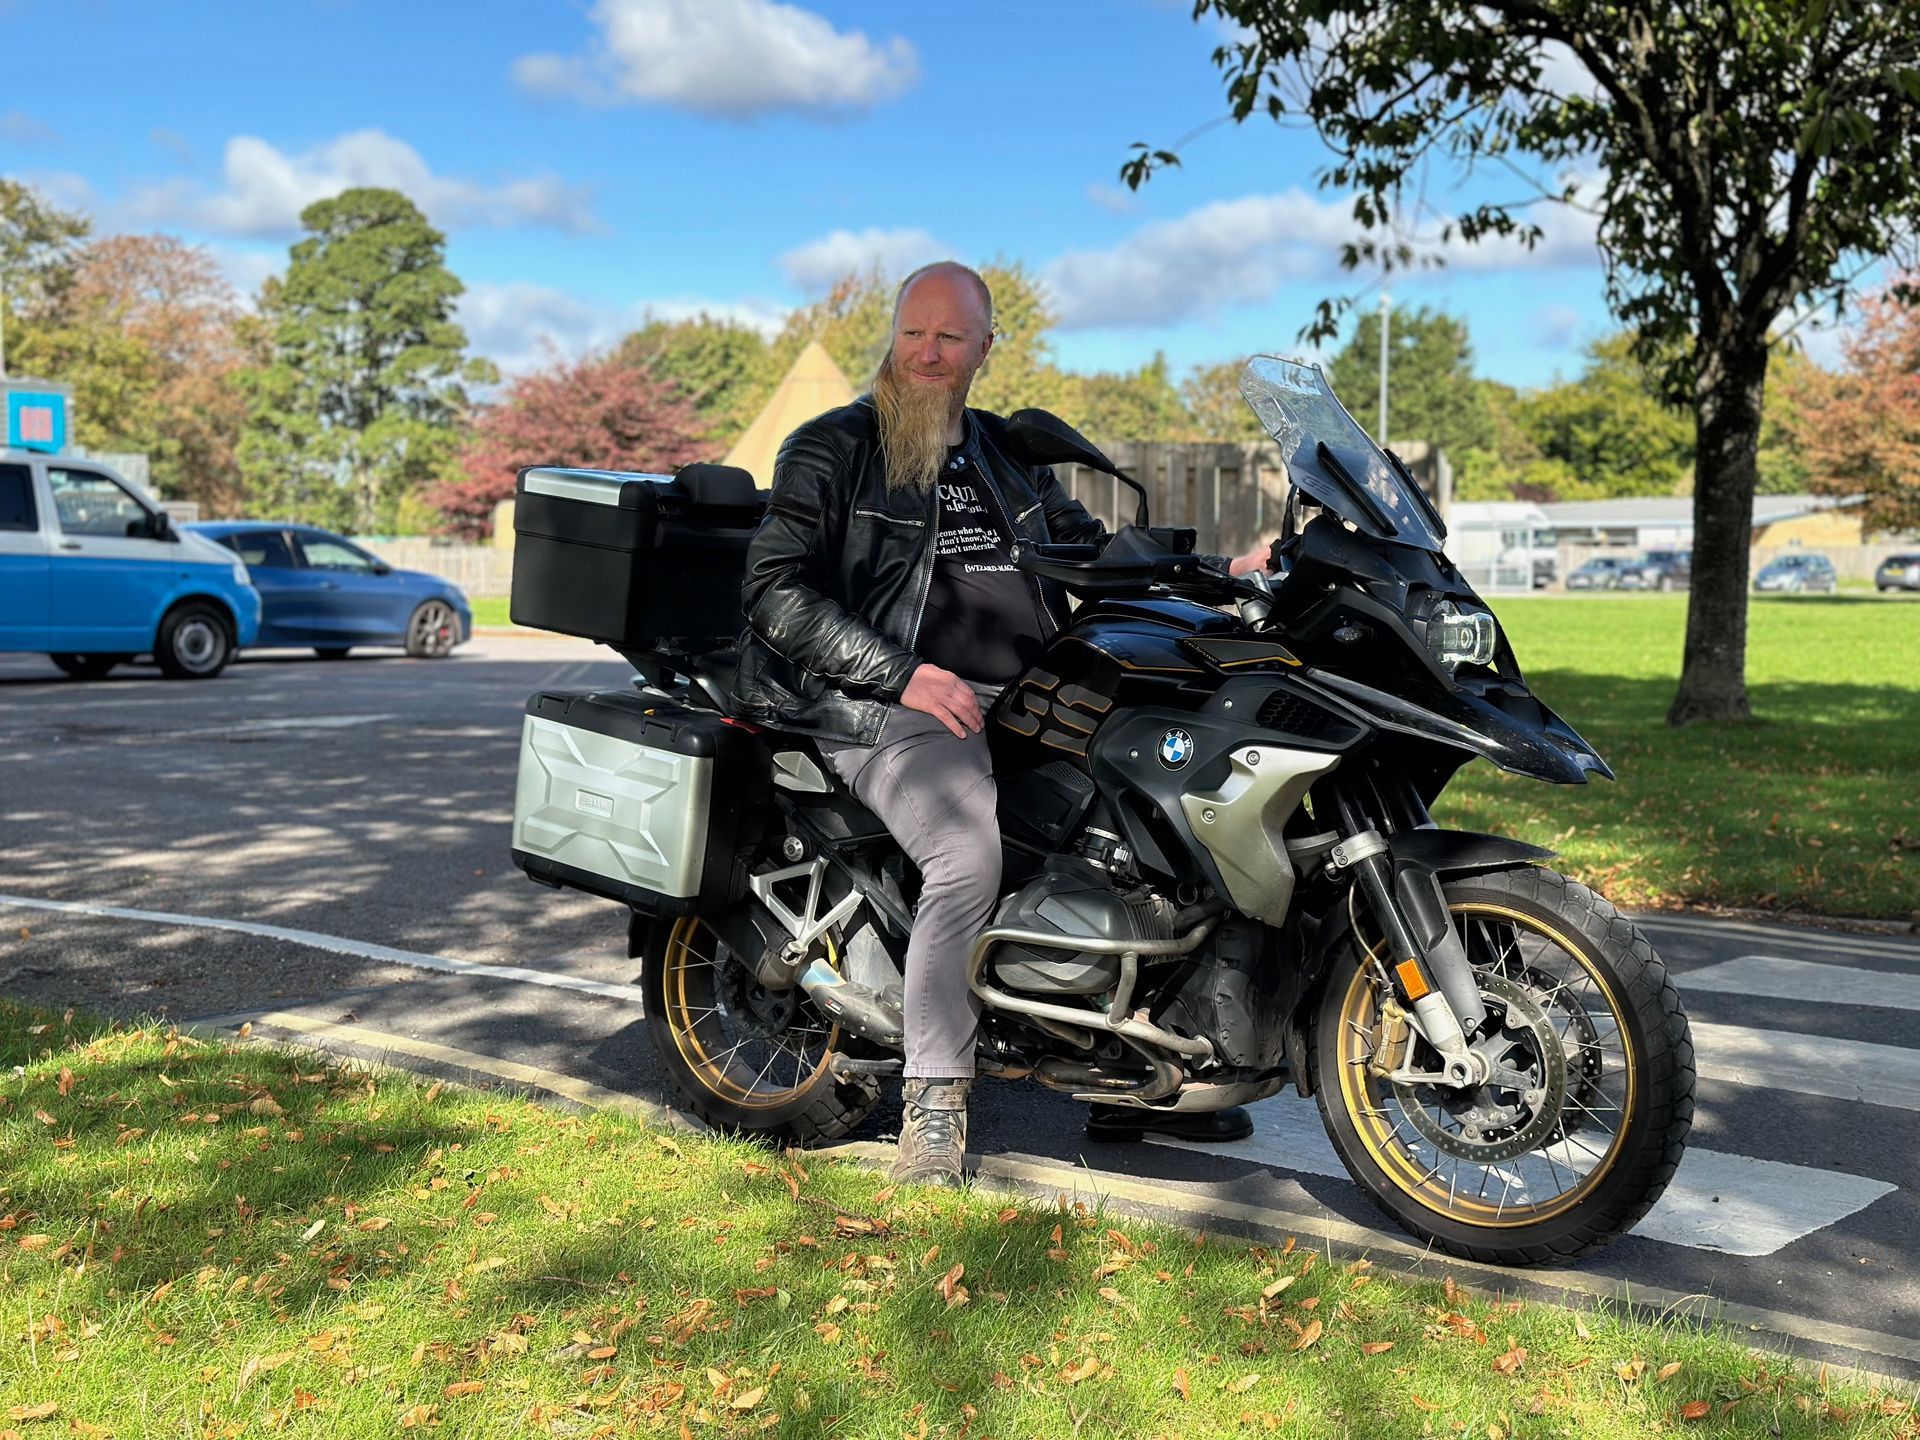
I'm a motorcyclist and an accountant, so the Motorcycle Action Group's (MAG) campaign to increase the approved motorcycle mileage allowance caught my attention from two directions. The allowance has been 24p per mile since April 2002. That's nearly a quarter of a century without an increase, despite everything that's happened to the cost of fuel, servicing, insurance and generally keeping a vehicle on the road. Meanwhile, the approved rate for cars and vans increased from 45p to 55p for the first 10,000 business miles earlier this year. The motorcycle rate stayed exactly where it was. Now, I don't think motorcycles and cars should necessarily attract the same mileage allowance. They have different running costs, and it's reasonable for the tax system to recognise that. But there's a difference between recognising those differences and leaving one rate untouched for 24 years while another is reviewed and increased. MAG is asking the Treasury to increase the motorcycle allowance to 45p per mile in the Autumn Budget on 28 October. Having looked at its arguments, I think MAG has made a reasonable case for the increase, and it's a campaign I'm happy to support. I should probably declare my interest here. I use my motorcycle for some business journeys in my accountancy practice, so I benefit from the mileage rules myself. But I don't cover particularly high business mileage, and the financial difference to me personally would be fairly modest. My interest is more in whether the system makes sense and treats different forms of transport consistently. There's also a distinction worth making between a mileage allowance and the amount of money somebody actually receives. An employer can reimburse an employee for qualifying business mileage at HMRC's approved rate without that payment normally being subject to tax. Where an employer pays less, the employee may be able to claim tax relief on the difference, which isn't quite the same as receiving the missing mileage allowance. For a self-employed person using the simplified mileage method, the allowance reduces taxable profit rather than providing a reimbursement. So an increase from 24p to 45p wouldn't automatically put another 21p per mile into everybody's pocket. What I particularly like about MAG's campaign is that it hasn't simply demanded the same rate as cars. Instead, MAG has put together research and modelling to support its proposal, including estimates of how much the change might cost the Treasury. Its modelling suggests that increasing the rate to 45p could cost the Treasury no more than £34 million a year, even under its higher-cost scenario. That's MAG's estimate, rather than an independently verified Treasury costing, but at least it gives us something specific to examine and challenge. And I think that's a worthwhile approach. If we're going to argue that an allowance is unfair, we should be prepared to explain what a fairer allowance might look like and what changing it could cost. There's another aspect of the policy that interests me. We tend to think of mileage rates as if somebody at the Treasury has worked out the average cost of running each type of vehicle and arrived at a carefully calculated figure. In reality, the Treasury considers a range of factors when setting these rates, rather than applying one fixed cost formula. That seems entirely reasonable. Different vehicles have different costs, and there are wider questions about what forms of transport the government wants to encourage. Motorcycles generally occupy less road space than cars, particularly when parked, and can offer advantages in congested areas. They're not without environmental or other drawbacks, and I certainly wouldn't suggest that every motorcycle is especially economical to run. A large touring motorcycle and a small commuter bike are rather different propositions. But if wider policy considerations form part of the decision, it seems reasonable to ask whether motorcycles' potential contribution to reducing congestion and demand for road space is being given appropriate consideration. There's an interesting comparison with bicycles, too. Their approved mileage rate is 20p, just 4p less than motorcycles. I'm certainly not suggesting that the bicycle allowance should be reduced, and encouraging cycling is a perfectly legitimate policy objective. But it does raise the question of whether we're applying a consistent approach to different forms of transport, particularly if these allowances reflect wider policy considerations as well as running costs. Ultimately, I'd like to see mileage allowances based on current evidence, with a clear explanation of the reasoning behind them. If that produces different rates for different vehicles, fine. What is harder to justify is a motorcycle rate that hasn't changed since 2002, particularly when the car rate has recently been increased. MAG has made its submission to the Treasury, and the decision now rests with the government. Whether the Chancellor accepts the proposed 45p rate remains to be seen. I hope the campaign succeeds. Not because I expect to make a fortune from claiming a few extra pence on my own business journeys, but because I think there's a good case for reviewing an allowance that has been overlooked for far too long. You can read MAG's campaign and the reasoning behind its proposal here: https://mag-uk.org/a-pay-rise-for-motorcyclists-its-down-to-the-budget-now/ With the Budget due on 28 October, we shouldn't have too long to wait to see whether the Treasury agrees.
The UK economy grew faster than expected in July, with artificial intelligence (AI) potentially playing a part in the surprise increase. According to the Office for National Statistics (ONS), gross domestic product (GDP) rose by 0.4% during July, despite economists predicting no growth at all. This follows a 0.3% increase in June and no growth in May. What's behind the unexpected growth? Much of July's growth came from the services sector, particularly computer programming. The ONS noted that IT businesses reporting the largest increases in turnover appeared to be linked to AI, although it's still difficult to put an exact figure on how much AI contributed to the economy's growth. Other factors, including the warm weather and the football World Cup, may also have played a part. Is the economy really getting stronger? While the figures are encouraging, economists aren't entirely convinced that the improvement will last. Capital Economics suggested that the resilience seen earlier in the year had continued into the second half, but warned that rising energy prices and borrowing costs could soon put pressure on growth. KPMG also pointed out that the headline figure doesn't tell the whole story. Retail and hospitality activity actually contracted during July, with higher fuel costs and elevated mortgage rates continuing to put pressure on household finances. It's a reminder that growth across the economy doesn't necessarily mean every business or household is feeling the benefit. What happens next? The figures were released shortly before the Bank of England's latest interest rate decision, which saw rates held at 3.75%, and ahead of Chancellor John Healey's first Budget in October. Healey described UK economic growth as still fragile, although he pointed out that Britain had recorded the fastest growth in the G7 during the first half of the year. For businesses, the figures offer some encouragement, particularly around the growing role of technology and AI. However, with costs and borrowing pressures remaining a concern, there's still plenty of uncertainty ahead. If you're running a business and want a clearer picture of how your finances are performing, get in touch. We can look at your figures and help you plan for what's ahead.
Your pension and inheritance tax: What changes in April 2027? For many people, pensions have traditionally been an important part of inheritance tax planning. Money left unused in a pension could generally be passed on to family members without forming part of the estate for Inheritance Tax (IHT). From 6 April 2027, that's changing. Under legislation introduced through the Finance Act 2026, most unused pension funds and lump sum death benefits will be included in the value of your estate when calculating Inheritance Tax. The change was first announced in October 2024, confirmed at the Autumn Budget in November 2025 and received Royal Assent on 18 March 2026. So this isn't simply a proposal that might happen. The legislation is already in place, with the new rules applying to deaths from 6 April 2027. What does this mean for your pension? Currently, most unused defined contribution pensions, including personal pensions, SIPPs and workplace pension pots, generally sit outside your estate for Inheritance Tax purposes. From April 2027, money remaining in these pensions when you die will normally be included alongside your property, savings and other investments when calculating the value of your estate. This includes pension funds you haven't yet accessed, money remaining in drawdown and most lump sum death benefits. There are, however, some important exceptions. Death-in-service lump sums and certain dependants' pensions will remain outside the new charge. Pension benefits left to a spouse, civil partner or registered charity will also continue to benefit from the existing Inheritance Tax exemptions. Defined benefit pensions, often called final salary pensions, are generally less affected because they don't usually involve an unused pension pot that can be passed on. Annuities are treated differently depending on their structure, although a joint-life annuity continuing to pay an income to a surviving spouse or civil partner isn't affected by these changes. Why could more families face inheritance tax? Inheritance Tax is normally charged at 40% on the value of an estate above the available allowances. The standard nil-rate band remains at £325,000, with an additional residence nil-rate band of up to £175,000 available in qualifying circumstances. The residence allowance begins to reduce where an estate exceeds £2 million. These thresholds are now frozen until April 2031. Bringing unused pensions into the calculation means that some estates which previously fell below the Inheritance Tax threshold could become liable for tax. HMRC estimates that, of approximately 213,000 estates expected to hold inheritable pension wealth in 2027/28, around 10,500 will face an Inheritance Tax bill for the first time. A further 38,500 estates are expected to pay more, with the average additional bill estimated at around £34,000 where pension assets are included. The measure is expected to raise an additional £710 million in 2027/28, increasing to £1.665 billion annually by 2030/31. How much difference could it make? Let's say you have a SIPP worth £150,000 which you intend to leave to your adult son. If the rest of your estate has already used up your available Inheritance Tax allowances, that £150,000 could currently pass to him without an Inheritance Tax charge. From April 2027, it would instead be included in your estate. At 40%, that could mean an additional £60,000 in Inheritance Tax, leaving £90,000. And there's another consideration. If you die aged 75 or over, your beneficiary will normally also pay income tax when withdrawing the inherited pension. Using the same example, if your son is a higher-rate taxpayer and pays 40% income tax on the remaining £90,000, that could mean a further £36,000 in tax. He would be left with £54,000 from the original £150,000 pension: a combined tax charge of approximately 64%. Of course, this is a simplified example. The actual position depends on the value of the wider estate, available allowances, exemptions and the beneficiary's tax circumstances. Pension benefits inherited following a death before age 75 can normally be withdrawn free of income tax, subject to the relevant conditions, including the two-year payment rule. Does this mean you should change your retirement plans? Not necessarily, but it does mean some existing plans may be worth reviewing. Many people have deliberately left their pensions untouched during retirement, using savings and other investments first. The thinking was that pensions could continue growing tax-efficiently and eventually pass to beneficiaries outside the estate for Inheritance Tax. From April 2027, that second advantage will generally disappear. For some people, it may make sense to reconsider the order in which they draw retirement income. However, there isn't a single approach that will suit everyone, and decisions about pension withdrawals should be discussed with a regulated financial adviser. It's also worth remembering that the tax advantages of saving into a pension haven't disappeared. Income tax relief on contributions, employer contributions and tax-free investment growth remain available. The standard annual allowance for 2026/27 is £60,000, although this can be reduced to as little as £10,000 for certain higher earners. Don't forget your will and pension nominations One area that's particularly worth checking is who you've nominated to receive your pension when you die. Many people have nominated children or grandchildren rather than a spouse, partly because of the previous Inheritance Tax advantages. Those nominations may still reflect your wishes, but the tax consequences could now be quite different. It's sensible to review your pension nominations alongside your will, any life insurance arrangements and your wider estate planning. The existing Inheritance Tax gifting rules also remain available, including the £3,000 annual exemption and the seven-year rule for larger gifts. From 6 April 2026, the £2.5 million allowance for 100% agricultural and business property relief also became transferable between spouses and civil partners. Another important change is that responsibility for reporting and paying any Inheritance Tax due on pension wealth will fall to the personal representatives dealing with the estate, rather than the pension provider. Pension beneficiaries can also be held liable for tax on the pension benefits they receive. Executors will therefore need to know what pensions exist and understand the additional responsibilities involved. There's still time to prepare The new rules apply across the UK, although the income tax treatment of pension withdrawals can differ for Scottish taxpayers because Scotland has its own income tax rates and bands. HMRC's Inheritance Tax receipts already reached a record £8.5 billion in 2025/26, and these changes are expected to increase the number of estates facing a liability. The important point is that pensions can no longer automatically be treated as separate from inheritance tax planning. That doesn't mean everyone needs to make drastic changes. For many families, particularly where pension benefits pass to a surviving spouse or civil partner, the immediate impact may be limited. But if your existing arrangements were made with the assumption that your pension would remain outside your estate, now is a good time to check whether they still achieve what you intended. If you're concerned about how the April 2027 changes could affect your family's finances, get in touch. We can review the tax implications and help you understand where further estate or pension planning advice may be needed
More than six in 10 UK millionaires have considered leaving Britain because of high taxes, according to new research from investment platform Wealth Club. The findings come alongside reports that hedge fund billionaire Chris Rokos is moving his tax residency to Greece, raising further questions about whether the UK's tax environment is encouraging wealthy individuals to look elsewhere. How many millionaires are actually considering leaving? Wealth Club surveyed more than 300 of its millionaire clients, who had an average wealth of £4.5 million. Of those surveyed, 61% said they had considered becoming non-UK tax resident. However, there's an important difference between considering a move and actually planning one. Just 16% said they were actively considering leaving the UK, while 36% said they had never thought about it. The research also challenges the assumption that most millionaires have inherited their wealth. Some 40% said they had made most of their money through employment, 33% through investments and 12% through starting a business. Only 2% identified inheritance as their main source of wealth. Tax rises remain a major concern Perhaps unsurprisingly, tax was high on the list of concerns among those surveyed. Almost all respondents (97%) believe taxes will rise over the next year, with inheritance tax, potential wealth taxes and capital gains tax causing the greatest concern ahead of the Budget. Of course, expecting taxes to rise doesn't necessarily mean they will, but the figures suggest considerable uncertainty among wealthy individuals about the direction of UK tax policy. Why is Greece attracting attention? The research comes amid reports that Chris Rokos, founder of Rokos Capital Management, is relocating his tax residency to Greece. Greece offers qualifying non-domiciled individuals a tax arrangement involving a flat annual charge of €100,000 (approximately £85,000) for up to 15 years. Rokos reportedly paid £330 million in tax last year, while his firm recorded revenues of £1.23 billion in 2025. His reported move illustrates the significant differences that can exist between countries' tax systems, particularly for individuals with substantial wealth and international financial interests. What does this mean for the UK? Alex Davies, founder and CEO of Wealth Club, warned that further tax increases could encourage more wealthy individuals to consider moving abroad. He pointed out that almost all those surveyed had built their wealth themselves, arguing that making Britain less attractive for saving and investing risks encouraging wealth creators to look elsewhere. Whether those considering a move actually follow through remains to be seen. The survey shows that far more millionaires have thought about leaving than are actively planning to do so. For anyone considering a change in tax residency, however, it's worth remembering that the tax implications are rarely straightforward. Becoming non-UK tax resident involves more than simply moving abroad, and the rules surrounding residence, income, gains and existing UK assets all need careful consideration. If you're concerned about how changes to the tax system could affect your finances, get in touch. We can talk through your circumstances and help you understand your options.
Most small business owners want to grow. More customers, more sales and more profit are generally good things. But there's a point where increasing turnover doesn't necessarily mean your business is becoming more successful. I was reminded of this recently while looking at the figures for my own business. Revenue is growing, recurring income is moving in the right direction and, on paper, everything looks pretty healthy. Then I looked at the hours. When growth starts taking up more than it gives back Like any owner-managed business, there's only so much time available. Eventually, taking on another customer doesn't just mean more revenue. It means another deadline, another email conversation, another set of records to review and another demand on your time each month. Of course, being busy because people want to work with you is a nice problem to have. But it's easy to assume that because taking on the last ten customers worked well, the next ten will be just as straightforward. At some point, capacity needs to become part of your financial planning. That doesn't necessarily mean employing somebody. It might mean reviewing your prices, improving processes, investing in better software, automating repetitive tasks or delegating work that doesn't require your particular expertise. More often than not, it's probably a combination of these things. Not all new business is good business Let's say a new customer would bring in an additional £200 a month. If you've got plenty of spare capacity, that's another £2,400 a year in turnover. Lovely. But if you're already stretched, there are a few other questions worth asking. How much work comes with that £200? Who's going to do it? What else could that time be spent on? And, perhaps most importantly, does taking on that customer actually move your business in the direction you want it to go? These are questions that turnover figures alone won't answer. A business that's increased turnover by 20% isn't necessarily 20% better off. If that growth means the owner is working every evening and weekend, customer service is beginning to suffer and there's no room to deal with anything unexpected, something eventually has to give. On the other hand, a business could increase its prices, lose a handful of customers and see very little change in turnover, but end up making more profit with considerably less pressure on the owner's time. Which of those businesses is really in a better position? The hidden cost of your own time One of the difficulties with running your own business is that your extra hours are remarkably good at hiding inefficiencies. There's no supplier invoice for staying at your desk until 10pm. Your accounts don't show an additional expense every time you answer emails on a Sunday afternoon. The work gets done, customers are looked after and the numbers might suggest everything is running smoothly. Until you run out of hours. And that's when the cracks can start to appear. I'm certainly not suggesting I've got all the answers myself. Looking at my own figures was a useful reminder that growth brings its own challenges, and what worked for a business at one stage won't necessarily work at the next. Perhaps it's time to ask a different question Rather than simply asking "How can I get more work?", perhaps the more useful question is "If I get more work, how is my business going to deliver it?" If your business is growing but your own time is increasingly becoming the limiting factor, it might be worth looking at things from a slightly different angle. Not just how much you're earning, but how much time that income takes to generate, which customers and services are genuinely profitable, and what might need to change to create capacity for the future. Because ultimately, a successful business shouldn't just be getting bigger. It should be working better, too. These are exactly the sorts of conversations I enjoy having with business owners. If you'd like to take a closer look at your figures and what they mean for your business, I'd be happy to help. Get in touch or find out more.
Higher petrol, diesel and airfare costs push inflation further above the Bank of England's target UK inflation rose again in August, with higher fuel and travel costs putting further pressure on household and business finances. According to the Office for National Statistics (ONS), inflation reached 3.1% in the year to August , up from 2.9% in July , driven largely by rising petrol, diesel and airfare costs. For businesses and households that had been hoping inflationary pressures were continuing to ease, the latest figures are a reminder that costs can change direction fairly quickly. Fuel prices rise sharply Petrol prices reached their highest level in almost four years during August. The average cost of a litre of petrol increased by 9.1p to 161.3p between July and August , the highest level recorded since November 2022. Diesel prices also rose sharply, while overall motor fuel costs were 23% higher than in the same month last year . The increases follow continued disruption to global oil supplies linked to conflict in the Middle East. Oil prices rose above $91 a barrel , compared with around $73 before hostilities began , and have since moved above $100 a barrel . For businesses reliant on vehicles, deliveries or transport, those increases can quickly feed through into day-to-day operating costs. Food inflation remains steady – for now Food and drink price inflation remained unchanged at 1.3% . That suggests the higher energy costs have yet to filter through significantly into other sectors, although businesses will naturally be watching closely to see whether that changes over the coming months. Rising energy and transport costs don't necessarily stay confined to the petrol station. They can increase the cost of producing and moving goods, which can eventually affect prices elsewhere. What could happen to interest rates? The latest increase takes inflation further away from the Bank of England's 2% target . At its September meeting, the Bank's Monetary Policy Committee voted 6–3 to keep interest rates at 3.75% , with three members instead voting for an increase to 4% . Some economists believe inflation could reach around 4.1% by the end of the year as businesses continue passing higher energy costs on. Paul Dales, chief UK economist at Capital Economics, summed up the expectation rather simply: "Everyone knows that bigger rises in inflation are on their way." What about the wider economy? There was some more positive news in the latest economic figures. The UK economy grew by 0.4% in July , supported by investment in artificial intelligence, although growth had slowed during the second quarter. Taken together, the figures give us a fairly mixed picture. The economy is growing, but businesses and households are once again dealing with increasing inflation and significantly higher fuel costs. For business owners, that's another reason to keep a close eye on margins, cashflow and pricing rather than simply looking at turnover. Final thoughts A rise from 2.9% to 3.1% might not sound dramatic in isolation, but the underlying increases in fuel and energy costs are worth watching. Businesses with significant transport, delivery or energy costs may feel the impact particularly quickly, while further increases could eventually feed through into supplier prices and other overheads. You can't control inflation or global oil prices, but you can understand what rising costs are doing to your own numbers. Regularly reviewing costs, margins and cashflow can help you spot pressure early and decide whether prices, budgets or plans need to change. If you'd like to discuss what rising costs could mean for your business or personal finances, I'm always happy to have a straightforward conversation. Talk to us about your finances.
A practical guide for sole traders and landlords preparing for the next stage of MTD for Income Tax Making Tax Digital for Income Tax is already here for some sole traders and landlords, but from 6 April 2027 it will apply to a much larger group. The system requires those within scope to keep digital business records and send HMRC a short online update every three months, rather than relying on one Self Assessment return each year. It has applied since 6 April 2026 to sole traders and landlords with qualifying income over £50,000 . From 6 April 2027 , that threshold falls to £30,000 of combined self-employment and property income . For those joining next, the change is less about how much tax you pay and more about how you keep your records and report information to HMRC. Four quarterly updates are followed by a year-end final declaration – similar in substance to the annual tax return many people are familiar with, but submitted through compatible software rather than HMRC's own online service. In other words, the days of handing over a shoebox of receipts once a year are coming to an end for those affected. More than 436,000 sole traders and landlords successfully submitted their first MTD for Income Tax quarterly update, and more than 570,000 had signed up to the service , HMRC confirmed as at 12 August 2026. The next wave is expected to be considerably larger. If your combined income from self-employment and property sits between £30,000 and £50,000 , your 2025/26 tax return is the one HMRC will use to decide whether you need to join from 6 April 2027. That means the time to work out whether you're affected – and prepare for it – is now, rather than next spring. The key points The £30,000 threshold is based on combined gross self-employment and property income before expenses are deducted . If your qualifying income exceeds that amount, based on your 2025/26 tax return, you'll need to join MTD for Income Tax from 6 April 2027. Once you're within the system, you'll need to make four quarterly updates plus a final declaration , all through compatible software. For jointly owned rental property, only your own share of the rental income counts towards your qualifying income, rather than the property's total income. There is another important difference for those joining in 2027: unlike the first intake in 2026, there is no penalty-free grace year for quarterly updates . The points-based penalty regime can apply from the outset. Partnerships and limited companies aren't yet included, while qualifying income of £20,000 or less remains automatically exempt. What is Making Tax Digital for Income Tax? MTD for Income Tax is HMRC's system for reporting self-employment and property income digitally throughout the year, alongside an annual final declaration. It doesn't introduce a new tax. Income Tax, Class 4 National Insurance and the underlying rules for calculating profit all remain the same. What changes is the reporting process. Anyone within scope must keep digital records of their self-employment and property income and expenses, send HMRC a quarterly update every three months and submit a year-end final declaration by 31 January , using compatible software rather than HMRC's own online service. You can't submit your final declaration for the year until all four quarterly updates have been sent. The rules apply in the same way across England, Scotland, Wales and Northern Ireland. Scottish taxpayers pay Income Tax using different rates and bands, but that affects how much tax is due rather than whether MTD applies. The three thresholds – and when they apply MTD for Income Tax is being introduced in three stages. The threshold is based on qualifying income – broadly, your gross self-employment and property income before expenses – declared on a particular year's tax return. Those with qualifying income over £50,000 in 2024/25 became subject to MTD from 6 April 2026 . Those with qualifying income over £30,000 in 2025/26 will join from 6 April 2027 . The threshold then falls again, with those earning over £20,000 in 2026/27 due to join from 6 April 2028 . HMRC reviews the relevant Self Assessment return each year and writes to anyone who has crossed the applicable threshold, confirming that they need to join from the following April. It's important, however, not to rely entirely on receiving that letter. Responsibility for checking whether you need to comply ultimately remains with you. For the £30,000 threshold, your 2025/26 tax return, due by 31 January 2027 , is the one that matters. Because that return relates to income you've already earned, some people may only discover they're affected a matter of weeks before the new rules begin. Working out your likely position now gives you much more useful notice. What counts as qualifying income? Qualifying income is your total turnover from self-employment and property added together, before expenses are deducted . It is based on the tax return submitted for the relevant year, rather than your profit. Suppose you're a personal trainer earning £22,000 from self-employment and also receive £9,500 in gross rent from a buy-to-let property you own outright. Your combined qualifying income is £31,500 . That's above the £30,000 threshold, so based on income declared on your 2025/26 return, you'd need to start using MTD for Income Tax from 6 April 2027. Not everything on your tax return counts towards the threshold. Employment income taxed under PAYE, dividends, State Pension and private pensions, and your share of profit from a partnership as an individual partner aren't included in qualifying income, although they may still need to be reported on your tax return. If you're UK resident, foreign property income counts alongside UK property income. If you're not UK resident, generally only UK property income and self-employment income declared on a UK tax return counts towards the threshold. What about jointly owned property? This is an important point for landlords. Only your share of the income from a jointly owned property counts towards your qualifying income, not the total amount generated by the property. Suppose you and your partner jointly own a rental property producing £40,000 in gross rental income each year , split equally. Your individual share is £20,000. If that's your only source of qualifying income, you'd be below the £30,000 threshold for the April 2027 start date, despite the property itself generating considerably more. If you're only ever told your share of the income after expenses have already been deducted, rather than seeing the gross rent, HMRC will normally use that net figure for your qualifying income instead. Any other self-employment or property income in your own name is then added to determine your total. Who isn't affected – at least for now? Partnerships don't currently need to use MTD for Income Tax and HMRC hasn't yet confirmed a start date for them. An individual partner with their own separate self-employment or property income could, however, still be caught personally. Limited companies sit outside these rules entirely because they pay Corporation Tax, while trusts and estates filing an SA900 return continue to report as before. Anyone whose qualifying income is £20,000 or less is automatically and permanently exempt, unless their circumstances change. A handful of other groups also qualify for exemptions, at least for now, including farmers and creative artists claiming averaging relief, foster and kinship carers, and people declaring non-UK residence. Most of these exemptions are temporary rather than permanent. What if your income moves around the threshold? Crossing the threshold isn't necessarily permanent. If you start a new self-employment or rental property partway through a tax year, HMRC will normally annualise the income to estimate your full-year qualifying income. This happens automatically for sole traders, while landlords need to annualise their own figures. If your qualifying income subsequently falls, however, you can't necessarily leave MTD immediately. Once you're using MTD for Income Tax, you can generally only opt out once your qualifying income has remained below the relevant threshold for three consecutive tax years . Selling your only rental property or closing your only self-employment can remove you from scope, but only once every source has stopped. HMRC still counts a ceased source towards qualifying income if another self-employment or property source continues. Where all your self-employment and property income has ceased since your last tax return, you won't need to use MTD for Income Tax, and you should tell HMRC before the start of the next tax year rather than waiting until your return is due. How do the quarterly updates work? Every three months, your software adds up your digital records for each business or property and sends HMRC a running total for the tax year to date, using the same income and expense categories as a Self Assessment return. These are summaries rather than complete tax returns, and no tax is calculated or due at this point. The quarterly deadlines are 7 August, 7 November, 7 February and 7 May . You need to submit an update even if you had no income or expenses during the period. You can also send an update early, up to ten days before the quarter ends, if you know there's nothing further to add. After each update, your software will show an estimated tax bill based on the information submitted. Of course, that estimate is only as useful as the information behind it. Adding other income, such as savings interest or dividends, during the year rather than leaving it until your tax return can make the running estimate more meaningful. Do you need to categorise every expense? Not necessarily. If your gross income from a self-employment or property business is below £90,000 , the current VAT registration threshold, you can report a single total expenses figure for that business each quarter rather than breaking every cost down by category. This is sometimes called consolidated or three-line reporting. The main exception is residential property finance costs, chiefly mortgage interest, which must always be reported separately because of the way tax relief on those costs is calculated. The £90,000 limit applies separately to each business or property source. Someone with two income streams could therefore use the simplified approach for one while needing full categories for another, depending on the turnover of each. What happens at the end of the year? After submitting your fourth quarterly update, you'll need to make your final declaration by the usual 31 January deadline . The difference is that this will now be done through compatible software rather than HMRC's own online service. The final declaration draws together all four updates and adds any other income and reliefs, including employment income, savings, dividends, Gift Aid or pension contributions. It then calculates your final Income Tax and Class 4 National Insurance liability. If you jointly let a property and chose not to include expenses in your quarterly updates, this is also the point at which you report them, by resending your fourth update before finalising the return. The tax payment deadline itself doesn't change. It remains 31 January . What software will you need? You'll need commercial software recognised by HMRC. Unlike the current online Self Assessment filing service, HMRC doesn't provide its own free MTD for Income Tax tool. There are two broad options: software that creates and stores your digital records directly, or bridging software that connects records held in a spreadsheet to HMRC's systems. Both free and paid products are available. Some deal with only part of the process, such as maintaining records or submitting updates, while others can handle everything through to the annual tax return. You can use more than one product if that works better for you, although only one product can be used for each individual submission. If you already use bookkeeping software for VAT or general record-keeping, it's worth checking whether it – or an available add-on – already supports MTD for Income Tax. Are there exemptions? Beyond the automatic £20,000 floor, the main route to exemption is digital exclusion . This can apply where age, disability or a health condition, a religious objection to digital communication, or a genuine lack of internet access makes it unreasonable to expect somebody to use compatible software. An exemption needs to be applied for and HMRC assesses each case individually. Simply preferring paper records, being unfamiliar with software or facing additional cost and time isn't enough on its own. Some other groups – including ministers of religion, Lloyd's underwriters, and people receiving Blind Person's Allowance or Married Couple's Allowance – are automatically exempt for now where this already appeared on their 2024/25 tax return, although this is expected to change at a later date. If your circumstances are unusual, it's better to check than assume either way. What happens if you miss a deadline? This is particularly important for those joining in April 2027. Late-submission penalties work on a points system. Each missed quarterly update or annual filing deadline earns one point . Once you reach four points, a £200 penalty applies , followed by another £200 for every deadline missed after that. Points normally expire 24 months after the deadline they relate to , provided you remain below the threshold. The first group joining MTD in 2026 was given a penalty-free first year for quarterly updates. That concession doesn't apply to the April 2027 intake. From 6 April 2027, the points-based system applies in full from the outset. It's therefore worth establishing the habit of meeting the deadlines from your very first quarter rather than assuming there will be a grace period. Late payment works differently, and here the first-year concession applies to everyone, regardless of which wave brings them into MTD. In your own first year under the scheme, HMRC allows 30 days rather than 15 before a late-payment penalty can apply, falling to 15 days from your second year. Once that grace period passes, unpaid tax attracts a penalty of 3% for the 2026/27 tax year, rising to 4% from 2027/28 , with a further equal penalty after 30 days and a daily annual charge from day 31. What should you do before April 2027? The biggest advantage of preparing early is simply avoiding a rushed move to new software and record-keeping habits immediately before your first deadline. Start by looking at your likely 2025/26 self-employment and property income . Remember that we're interested in turnover before expenses, not simply the profit you've made. If you're approaching or exceeding £30,000, start comparing software now. If you already use bookkeeping or VAT software, find out whether it can also deal with MTD for Income Tax. It's also a good time to get into the habit of recording income and expenses as they happen rather than gathering everything together once a year. Landlords with jointly owned properties should establish their actual share of the relevant income, as this can determine whether they're individually affected. And if you're not sure where you stand, ask sooner rather than later. We can check your qualifying income, help you choose suitable software and put a quarterly routine in place well before April. Final thoughts Making Tax Digital for Income Tax has already changed record-keeping for sole traders and landlords earning over £50,000. The £30,000 threshold arriving on 6 April 2027 will bring a considerably larger group into the system, many of whom have never previously needed to think about digital quarterly reporting. Crucially, the tax year that determines who joins next – 2025/26 – has already ended , and the return reporting that income is due by 31 January 2027 . The risk is waiting until an HMRC letter arrives, or until the first quarterly deadline is only weeks away. Choosing software and getting used to keeping records digitally takes time. If your combined self-employment and property income is approaching £30,000, or you're unsure how jointly owned property affects your position, it's worth looking at it now. We can check whether you're likely to be affected and help you get everything ready well ahead of April 2027. Talk to us about Making Tax Digital. You may find this article useful: Missed the MTD deadline? Here’s what happens next
Most business owners don’t expect their bookkeeping to be perfect every day. Nor should they. There will always be an invoice waiting to arrive, a payment that needs identifying or something that needs checking before we’re quite sure where it belongs. But there comes a point where we want to use the bookkeeping for something else, and at that point “nearly finished” can become a problem. There’s a difference between a judgement and an unknown This came up in a conversation recently. There was some year-end work to do and most of the bookkeeping was complete, but there were still a number of queries outstanding. Could we start the next piece of work anyway? Possibly, but first I wanted to know what was missing. There’s an important difference between knowing that the accounts contain a small discrepancy which isn’t worth spending any more time investigating, and having transactions missing that we haven’t yet identified. One is a judgement; the other is an unknown. Take a supplier invoice for £10,000 which hasn’t yet been entered into the accounts. If it hasn’t been paid, the bank can be completely reconciled and everything may appear fine. But the accounts are showing £10,000 too much profit and £10,000 too little owed to suppliers. Depending on what was purchased, the VAT position might be wrong as well. If all we’re trying to do is finish the bookkeeping, that’s something we need to correct, but the bigger problem comes when we start relying on those figures for something else. What happens when we rely on incomplete figures? We might use them to decide whether the company can afford a dividend, review its margins, prepare a cash-flow forecast or carry out some more specialist tax work. If that missing cost is relevant to the work we’re doing, we’ve now started answering a completely different question using incomplete information. The same applies to management accounts. There’s little value in producing a lovely report showing that gross margin has improved if some of the costs which should be included in it haven’t been recorded yet. The report itself can be perfectly accurate; it’s the information we’ve fed into it that’s wrong. Bookkeeping is the foundation This is one of the reasons I put quite a lot of emphasis on bookkeeping, even though bookkeeping isn’t really what I’m interested in. What I’m interested in is what we can do with the information afterwards. If I know the bookkeeping is reliable, we can start asking much more useful questions about how the business is performing, where the cash is going, whether margins are changing, what the next few months might look like and what the owners can safely take out of the business. There are increasingly clever tools available to help answer those questions. Accounting packages will produce reports at the click of a button, and forecasting and reporting software can turn the data into dashboards and some very impressive-looking graphs. None of them, however, can tell us about the invoice that never made it into the accounts. Finished doesn’t have to mean perfect That doesn’t mean I expect bookkeeping to achieve some impossible standard of perfection before we’re allowed to use it. Quite the opposite. Accounting involves judgement and materiality, and sometimes spending another hour trying to find a tiny difference makes absolutely no commercial sense. If I know there’s a £5 discrepancy and decide it isn’t worth another hour of somebody’s time to find it, I can make that decision knowing what I’m dealing with. What concerns me more is not knowing whether the difference is £5 or £5,000. That’s why clearing bookkeeping queries isn’t simply an exercise in making everything tidy before the accountant starts the “proper” work. The bookkeeping is the foundation for the proper work. The further we move from basic compliance into management accounts, forecasting, tax planning and financial advice, the more we’re relying on that foundation. Better analysis doesn’t compensate for worse information underneath it. So, when is the bookkeeping actually finished? Not necessarily when every last penny has been accounted for. For me, it’s when we’ve dealt with the important unknowns and understand anything that remains well enough to decide whether it matters. At that point, we have something much more useful than tidy books: we have numbers we can actually trust. If you’re running a business and aren’t confident that the numbers you’re looking at tell you what’s really going on, get in touch. We can have a chat about where the problems are and whether I can help you get to the point where your accounts are useful for more than filing the next return.
VAT Capital Goods Scheme Changes: What Businesses Need to Know The VAT capital goods scheme has changed, with new rules taking effect from 29 July 2026 . The changes increase the threshold for property-related assets and remove computers and computer equipment from the scheme altogether. For businesses investing in premises or equipment, it should mean fewer assets getting caught by a scheme that can involve monitoring and adjusting VAT for several years. The property threshold rises to £600,000 The biggest change is to land, buildings and civil engineering works. The expenditure threshold has increased from £250,000 to £600,000, excluding VAT . This means the capital goods scheme will now only apply where qualifying expenditure on these assets reaches at least £600,000. It’s quite a jump, but perhaps not surprising when you consider that the previous £250,000 threshold had been unchanged since the scheme was introduced in 1990 . Property prices have moved on rather a lot since then. As values increased, more small businesses found themselves having to deal with capital goods scheme calculations when buying or refurbishing relatively modest premises. HMRC says the higher threshold should reduce the number of assets falling within the scheme and remove some of those time-consuming calculations. Computers are removed from the scheme There’s another useful simplification for businesses investing in technology. Computers and computer equipment are no longer eligible for the capital goods scheme. Capital expenditure on these items incurred from 29 July 2026 will therefore fall outside it. The scheme requires businesses to monitor how certain capital assets are used over a number of years. If their use changes, the amount of VAT originally reclaimed may need to be adjusted. Removing computer equipment and raising the property threshold should therefore reduce the administrative burden, particularly for smaller businesses. What about existing assets? Importantly, the changes aren’t retrospective . Assets and expenditure that were already within the capital goods scheme before 29 July 2026 will continue to be dealt with under the previous rules. So, this isn’t a case of simply removing existing assets from your calculations because the thresholds have now changed. A change several years in the making This particular reform has taken a while to arrive. The Office of Tax Simplification first proposed changes in 2017 , followed by a call for evidence in July 2019 . Implementation took several more years, and the Office of Tax Simplification itself was subsequently abolished in 2022 , during Liz Truss’s short-lived Government. For businesses, though, the important point is that the new rules are now in force. If you’re investing significantly in property, refurbishing business premises or have assets already covered by the capital goods scheme, it’s worth making sure you know which set of rules applies. Talk to us about your finances.
What to check before you sell, gift, or transfer an asset. A little planning before a transaction can make a significant difference to the tax position Capital Gains Tax can arise in far more situations than simply selling an investment for a profit. Giving an asset to a family member, transferring ownership, exchanging one investment for another or even selling something for less than its full value can all count as disposals for Capital Gains Tax purposes. The tax is charged on the gain rather than the total amount you receive. However, what you ultimately pay depends on several factors, including the type of asset, what it originally cost, your income, previous losses, available tax reliefs and who receives the asset. Timing can make a difference too. HMRC's latest available annual statistics show that 378,000 taxpayers incurred Capital Gains Tax liabilities of £12.1 billion in 2023/24 , based on total taxable gains of £65.9bn . These remain the latest complete annual figures available as at 7 August 2026, with HMRC's next annual statistical release expected later in 2026. If you're considering selling, gifting or transferring a valuable asset, working out the tax position before committing to the transaction can prevent unexpected bills and identify reliefs that might otherwise be missed. What counts as a disposal? Capital Gains Tax, or CGT, generally applies when you dispose of a chargeable asset that has increased in value. Importantly, a disposal doesn't have to be a conventional sale. It can include selling an asset, giving it away, transferring ownership to somebody else, exchanging one asset for another or receiving compensation for something that has been lost or destroyed. That means you can potentially create a CGT liability even where you've received little or no cash. Common chargeable assets include second homes and investment properties, shares held outside an ISA, business interests, land, certain valuable personal possessions and cryptoassets. Your main home will often qualify for Private Residence Relief, but that exemption isn't automatic in every situation. The Capital Gains Tax allowance for 2026/27 Individuals have a £3,000 annual exempt amount for 2026/27 . This means the first £3,000 of your net chargeable gains for the tax year can normally fall outside CGT. For trusts, the amount is £1,500 . The allowance applies across your taxable disposals for the whole year rather than separately to each asset, and you can't carry an unused annual exempt amount forward. For example, suppose you make an £8,000 gain on shares and a £2,000 loss on another investment . Your net gain is £6,000. After deducting the £3,000 annual exempt amount, £3,000 would remain chargeable to CGT , assuming no other gains, losses or reliefs apply. The reduction in the annual exempt amount over recent years means relatively modest gains can now create a reporting or tax liability. What are the CGT rates for 2026/27? For disposals from 6 April 2026 , the main CGT rates for individuals are 18% where a gain falls within the available basic rate band and 24% where it falls above it. Gains qualifying for Business Asset Disposal Relief are taxed at 18% , as are gains qualifying for Investors' Relief . The standard Personal Allowance remains £12,570 for 2026/27 , while the UK basic rate limit used for CGT purposes is £37,700 . Your income and gains interact when determining how much of a taxable gain falls at 18% and how much falls at 24%. Special rules apply when calculating the available basic rate band for Scottish taxpayers. Someone who is already above the relevant basic rate band will normally pay 24% on taxable gains unless a specific relief provides a different rate. Someone with unused basic rate band may pay 18% on some or all of their gain. That's why your expected income for the year should form part of any CGT calculation. Work out the real gain before estimating the tax CGT doesn't normally apply simply to the difference between what you originally paid and what you receive. Certain costs can reduce the chargeable gain. Depending on the asset, these may include the original purchase price, Stamp Duty or Stamp Duty Land Tax paid on acquisition, legal and professional fees associated with buying and selling, valuation fees and qualifying expenditure that enhanced the asset's value. For property, an extension or other capital improvement may qualify, whereas normal repairs and maintenance generally won't. The improvement normally needs to remain reflected in the asset when it is disposed of. Keeping purchase documents and records of improvement expenditure can therefore make a significant difference many years later. HMRC expects taxpayers to retain evidence including contracts, receipts, invoices, professional fees and valuations used when calculating gains. Gifting an asset doesn't automatically avoid CGT One of the biggest misconceptions around CGT is that giving an asset away avoids tax because you haven't received any money. Usually, it doesn't. When you give a chargeable asset to another person, HMRC will generally treat the disposal as taking place at its market value on the date of the gift . The same principle can apply if you deliberately sell an asset for less than it's worth to help the buyer. Suppose, for example, you bought an investment property for £150,000 and it is now worth £300,000 . Giving the property to an adult child for nothing doesn't normally produce a CGT disposal value of £0. Broadly, the calculation starts by treating you as disposing of it at its £300,000 market value. The resulting gain then needs to be calculated after allowable costs and any available reliefs. That can leave you with a tax bill without the cash proceeds that would normally help you pay it. Transfers to children, grandchildren and other family members should therefore be considered carefully before the gift takes place. Inheritance Tax, Stamp Duty Land Tax and other tax rules may also apply depending on the circumstances, so CGT shouldn't be considered in isolation. Different rules apply to spouses and civil partners Transfers between spouses and civil partners who live together generally take place on a no gain/no loss basis for CGT. The person transferring the asset doesn't normally realise an immediate taxable gain. Instead, the receiving spouse or civil partner effectively inherits the existing CGT history of the asset. That can create legitimate planning opportunities. Before selling an investment, for example, couples may want to consider ownership where one spouse has an unused annual exempt amount, capital losses available, more unused basic rate band or already owns a different proportion of the asset. Any transfer needs to represent a genuine change in beneficial ownership. It should happen before the eventual disposal and shouldn't simply be recorded retrospectively once a sale has been agreed. It is also important to remember that transferring the asset doesn't eliminate the underlying gain. It changes who owns it and may therefore change how the eventual gain is taxed. Take care following separation or divorce Special CGT rules apply when spouses or civil partners separate. For disposals taking place on or after 6 April 2023 , separating spouses and civil partners can generally make no gain/no loss transfers until the earlier of the end of the third tax year after the tax year in which they ceased living together , or the date on which a court grants the divorce or dissolution. Where assets are transferred under a formal divorce or separation agreement or relevant court order, no gain/no loss treatment can continue without the normal three-year limit. There are also specific provisions covering the former family home and situations where one party retains a financial interest in a future sale. The tax position is therefore best considered while the financial arrangements are being agreed, rather than after assets have already changed hands. Check the position before selling property An investment property, second home, land or other property that doesn't qualify fully for Private Residence Relief can produce a taxable gain. Allowable acquisition, disposal and improvement costs should be established before calculating the liability. If CGT is due on the sale of most UK residential property, it generally needs to be reported and paid within 60 days of completion . That's considerably sooner than the normal Self Assessment deadline, so property owners should calculate the expected gain and identify the necessary records before completion where possible. Don't assume your main home is always completely exempt Private Residence Relief (PRR) means many people pay no CGT when selling their main home. You can only have one PRR residence at a time . Full relief will normally apply where the property has been your only or main home throughout your ownership, you haven't let part of it out in a way that restricts relief, no part has been used exclusively for business, the property and grounds meet the relevant conditions and you didn't acquire it primarily to make a gain. More care is needed if you've owned more than one home, let the property for part of your ownership, lived elsewhere for extended periods, used part of it exclusively for business, have significant land or grounds, or changed how the property was occupied over time. Where a property has qualified as your main residence at some point, the final nine months of ownership will generally qualify for Private Residence Relief even if you were no longer living there. Different provisions can apply for certain disabled people and long-term care home residents. Letting Relief is also much more restricted than it was historically. It is generally relevant where you shared occupation of the home with a tenant, and relief can be limited to a maximum of £40,000 per owner , subject to the detailed conditions. Property size can affect relief too Private Residence Relief normally includes the home and its garden or grounds. The standard permitted area is 0.5 hectares , including the site of the dwelling. A larger area can sometimes qualify where the character and size of the property make the additional land necessary for the reasonable enjoyment of the residence, but additional conditions apply. This can become particularly relevant with larger homes, substantial gardens or where part of the land is sold separately from the house. Review shares and investments before selling You may have to pay CGT when disposing of shares, unit trusts and other investments held outside tax-exempt wrappers. Shares held within an ISA don't create a CGT liability when sold. UK Government gilts and certain other investments are also exempt. Where shares have been accumulated over several years, establishing their CGT cost can involve more than simply looking at the price of the first purchase. Special identification rules can apply when you buy and sell shares in the same company around the same date. Corporate actions, reorganisations, rights issues and previous transfers between spouses can also affect the base cost. Before making a substantial disposal, it's worth checking the complete acquisition history rather than relying solely on a current investment-platform statement. Crypto transactions can create taxable disposals Cryptoassets are also within the CGT rules for many individual investors. A disposal can occur when you sell tokens for sterling or another currency, exchange one type of token for another, use cryptoassets to buy goods or services, or give tokens to another person other than a spouse, civil partner or qualifying charity. Exchanging Bitcoin for another cryptoasset, for example, can create a taxable disposal even though no sterling ever enters your bank account. Good transaction records become particularly important if you're trading through several exchanges or wallets. Valuable personal possessions can fall within CGT CGT isn't restricted to property and investments. Certain personal possessions can become chargeable where their disposal value exceeds £6,000 . Examples include jewellery, paintings, antiques, coins, stamps and collections. Private cars are generally exempt, while certain assets with a predictable useful life of 50 years or less can also qualify for separate exemptions. Special rules apply when individual items form a set, so dividing a valuable collection into separate transactions doesn't necessarily produce a separate £6,000 limit for each item. Consider relief before gifting business assets A gift of a business or shares in a family trading company can create a sizeable gain even where the recipient pays nothing. Gift Hold-Over Relief may allow qualifying gains to be deferred. Broadly, the donor doesn't pay CGT immediately on the part of the gain successfully held over. Instead, the recipient takes a reduced acquisition cost, meaning the deferred gain can become taxable when they eventually dispose of the asset. The relief can apply to qualifying business assets and certain shares, including shares in some unlisted trading companies. A joint claim will normally be required. This can make the relief useful for family business succession, but it is important to understand that it defers tax rather than necessarily removing it . A change to the calculation of Gift Hold-Over Relief for certain company shares has been announced to take effect for disposals from 6 April 2027 . It doesn't apply to 2026/27 disposals, but anyone planning a business succession extending into the next tax year should review the legislation before proceeding. Business Asset Disposal Relief changed in April 2026 People selling a business or qualifying shares should also check whether Business Asset Disposal Relief (BADR) applies. For qualifying disposals made from 6 April 2026, the BADR rate is 18% . That increased from 14% in 2025/26 and 10% for qualifying disposals on or before 5 April 2025 . The lifetime limit on qualifying BADR gains remains £1 million . Conditions normally need to have been met for at least two years before disposal , so eligibility should be checked well before a business or share sale completes. Don't forget capital losses Previous investment losses can reduce a future CGT bill if they've been properly claimed. Allowable losses arising in the same tax year are generally set against gains first. Unused losses from earlier years can then be used against gains, although the rules are designed so brought-forward losses don't normally reduce gains below the annual exempt amount unnecessarily. A loss doesn't always have to be claimed immediately. HMRC generally allows a taxpayer to claim an allowable capital loss up to four years after the end of the tax year in which the disposal took place . Before selling a valuable asset, it's therefore worth checking whether you have previously reported losses available. The tax year can affect the result The tax year runs from 6 April to the following 5 April . Where you have control over the timing of a disposal, completing transactions in different tax years can sometimes change the CGT result because each year has its own annual exempt amount and income position. However, determining the CGT disposal date isn't always as simple as looking at when the money reaches your bank account. For many transactions completed under an unconditional contract, the date of the contract determines the CGT disposal date , rather than the date payment or completion takes place. That can determine the tax year, applicable rate, available annual exemption and reporting requirements. For UK residential property, the separate 60-day reporting deadline is generally measured from completion . Any tax-year planning therefore needs to happen before contracts become binding. Inheriting an asset produces a different CGT starting point Death doesn't normally create the same CGT charge as giving an asset away during someone's lifetime. For CGT purposes, assets inherited from an estate generally use their market value at the date of death as the beneficiary's starting value, subject to the relevant rules and any value agreed for Inheritance Tax purposes. If the beneficiary later sells the asset, the subsequent gain is broadly calculated by reference to that probate or date-of-death value rather than what the deceased originally paid. That's a significant distinction between lifetime gifts and inherited assets. However, Inheritance Tax and wider estate-planning considerations also need to be taken into account, so the CGT result shouldn't determine succession decisions by itself. What should you check before disposing of an asset? Before selling, gifting or transferring a significant asset, there are a number of things worth establishing. You need to know what you originally paid and whether you have evidence, the current market value – particularly for gifts or transfers between connected people – and any allowable acquisition, disposal or improvement costs. You should also check for previous capital losses, consider your other expected gains and taxable income for the year, and establish whether reliefs such as Private Residence Relief, Gift Hold-Over Relief or Business Asset Disposal Relief could apply. Ownership can matter too, particularly between spouses and civil partners, as can the precise CGT disposal date. Finally, consider how the transaction interacts with other taxes such as Inheritance Tax and Stamp Duty Land Tax, whether the 60-day property reporting deadline applies and, importantly, whether you'll have enough cash available to pay the resulting tax. The best time to consider all of this is before the transaction becomes binding . Once a sale has completed or an asset has legally changed ownership, many of the planning options that might have been available beforehand may no longer be possible. Capital Gains Tax should therefore be part of the decision to sell, gift or transfer an asset, rather than something you only think about when it's time to report the transaction. If you're planning to sell, gift or transfer an asset, speak to me before taking action so we can look at the potential Capital Gains Tax implications while there is still time to plan. Talk to us about Capital Gains Tax.
What Can Businesses Expect? We have a date for the next Budget. Chancellor John Healey will deliver his first Budget on Wednesday 28 October 2026 , just over three months after taking charge of the Treasury. Healey confirmed the date in a video announcement, saying the Government was moving quickly to restore hope and support communities across Britain. He succeeded Rachel Reeves as Chancellor on 20 July , following Andy Burnham’s appointment as Prime Minister. That gives the new Chancellor just 89 days to prepare his first major fiscal statement. Perhaps that relatively short run-up isn’t a bad thing. The lengthy build-up to the 2025 Budget brought plenty of speculation about what might or might not change, which inevitably made it more difficult for businesses and households to plan with any certainty. Moving money away from Westminster One theme we already know will feature heavily is devolution. Healey has said the Budget will aim to move money and decision-making away from Westminster and into communities across the country, making greater regional control an important part of the new Government’s economic plans. At the same time, he has been keen to stress that this won't mean abandoning financial discipline. The Chancellor has confirmed that the Government intends to continue meeting its existing fiscal rules, despite the pressures on the public finances and demands for further spending. Stability will matter to businesses Healey has also said the Budget should give businesses and families the stability they need to plan for the future. For businesses, that word stability is probably one of the more important parts of the announcement. Whatever measures eventually appear in the red box, knowing what you're dealing with makes planning, forecasting and investment considerably easier than trying to run a business against a backdrop of constant speculation. The challenge for Healey will be balancing the Government's ambitions for greater regional investment and control with its commitment to responsible borrowing and spending. This will be his first Budget as Chancellor and one of the earliest indications of how Andy Burnham's Government intends to put its economic plans into practice. For now, Wednesday 28 October is the date for the diary. Once we know what's actually in the Budget, I'll be looking beyond the headlines at what the announcements really mean for businesses and their owners. Talk to us about your business.
More than 4 in 10 taxpayers expected to join MTD had not registered before the first quarterly deadline Making Tax Digital (MTD) for Income Tax is now very much a reality for hundreds of thousands of self-employed people and landlords. According to HMRC, more than 500,000 people had signed up ahead of the first quarterly reporting deadline on 7 August . However, that still left an estimated 364,000 taxpayers – more than 4 in 10 of those expected to be within scope – unregistered before the deadline. HMRC had identified around 864,000 taxpayers with qualifying income above £50,000 who were expected to join MTD from the 2026/27 tax year . What was due on 7 August? The 7 August deadline covered both registration for MTD and submission of the first quarterly update, reporting income for the opening quarter of 2026/27. Those updates have to be submitted using MTD-compatible software , as HMRC doesn't provide its own online filing service for them. For anyone who missed the deadline, the important thing now is not to ignore it. HMRC has said it will send reminder letters to taxpayers who haven't met their obligations, with further figures on registrations and quarterly submissions expected to follow. Sign-ups are increasing HMRC says activity increased significantly as the deadline approached. Craig Ogilvie, HMRC's director of MTD, said almost 30,000 quarterly update obligations were recorded in a single day earlier in deadline week, adding that HMRC was "regularly breaking MTD sign-up and submission records". However, professional bodies have raised concerns about the number of taxpayers who had still not registered. ACCA senior technical advisory manager Yogesh Dhanak said the figures highlighted shortcomings in HMRC's awareness campaign and warned that implementation remained challenging. Given that more than four in ten of those expected to be within scope had yet to register before the deadline, it's clear that a significant number of people are still getting to grips with the new system. What if you've missed a quarterly deadline? There is some breathing space during the first year. There are no penalties for missing a quarterly update deadline during 2026/27 , although that doesn't mean the update can simply be ignored. Taxpayers are still required to submit the information. The more significant date to be aware of is 6 April 2027 . From then, the points-based late-submission penalty regime will apply. Under the system, a taxpayer will receive one point for each missed quarterly deadline . Once four points have accumulated, a £200 penalty will be charged. That makes the current tax year a useful opportunity to get familiar with the process and make sure your record-keeping and software are working properly before penalties come into play. Final thoughts MTD represents a significant change to the way many self-employed people and landlords manage their tax affairs. If you were supposed to join from 2026/27 and haven't yet registered or submitted your first quarterly update, it's worth dealing with it now rather than allowing the outstanding requirements to build up. And for those already submitting quarterly updates, now is the time to make sure the process is working smoothly. From 6 April 2027 , missed quarterly deadlines can start accumulating penalty points, so getting into good habits during this first year could save a lot of unnecessary hassle later. If you're unsure whether MTD applies to you, need help getting set up with compatible software or simply want somebody to take the headache out of the new requirements, talk to us about MTD. You may find this interesting: SPOTLIGHT ON: MTD for income tax
Late Payments: Protecting Your Cashflow and Getting Paid on Time You can make a perfectly profitable sale and still end up with a cashflow problem if the customer doesn’t actually pay you. By the time an invoice becomes overdue, you may already have paid staff, suppliers and even the tax associated with the work. The profit might exist on paper, but unfortunately you can’t pay the bills with an outstanding invoice. And this is far from a small problem. Research commissioned by the Department for Business and Trade and the Office of the Small Business Commissioner estimates that late payments cost the UK economy almost £11 billion a year . At any one time, around £26bn is owed to businesses in late payments , affecting more than 1.5 million businesses – around 28% of the UK business population . For those affected, the average amount outstanding is approximately £17,000 . Perhaps more concerning is the estimate that 14,000 businesses close each year because of late payments , while affected businesses spend an average of 86 staff hours a year simply chasing money they're already owed. There has been some improvement. Department for Business and Trade figures published in July 2026 show that large businesses paid suppliers in an average of 32 days during 2025 , with 15% of invoices paid late. When reporting began in 2018, that figure was 25%. But for SMEs in particular, protecting cashflow needs to start long before an invoice becomes overdue. When is a business payment actually late? The rules on late commercial payments apply to qualifying business-to-business transactions for goods and services. Where a payment date has been agreed, payment terms between private-sector businesses should usually be no longer than 60 days . A longer period can currently be agreed, but it must be fair to both parties. Public authorities are generally expected to pay within 30 days . If you haven't agreed a payment date, a commercial payment will normally become late 30 days after the later of the customer receiving the invoice or the goods or services being supplied. This is why clear payment terms matter. Simply putting "payment due" on an invoice isn't a substitute for agreeing proper terms beforehand. Your terms should establish when payment is due, how the customer can pay, what information they need to approve the invoice and what happens if they pay late. For larger projects, it may also make sense to use deposits, staged invoices or milestone payments rather than doing all the work before raising one large invoice. You may be entitled to charge interest Under the Late Payment of Commercial Debts (Interest) Act 1998, businesses can have a statutory right to charge interest when another business pays late. The statutory rate is 8% above the applicable Bank of England base rate . For these purposes, the reference rate is fixed for six-month periods. The Bank of England rate on 30 June applies from 1 July to 31 December, while the rate on 31 December applies from 1 January to 30 June. The Bank Rate was 3.75% on 30 June 2026 , making the statutory late-payment interest rate 11.75% a year for qualifying debts becoming late between 1 July and 31 December 2026. So, take a qualifying £5,000 invoice that becomes overdue during this period and remains unpaid for 45 days. At 11.75%, the statutory interest would be approximately £72.43 . Interest normally runs from the date payment becomes late until the customer actually pays. You do need to check your contract before applying statutory interest, though. If it already provides its own late-payment remedy or interest rate, the statutory regime may not apply. You may also be able to recover your costs Interest isn't necessarily the only amount you can claim. There is also fixed statutory compensation towards the cost of recovering a qualifying late commercial payment. For debts of up to £999.99, it's £40 . For debts between £1,000 and £9,999.99, it's £70 , and for debts of £10,000 or more, it's £100 . The charge applies to each qualifying late payment, and reasonable additional recovery costs may also be recoverable in appropriate circumstances. Going back to our £5,000 invoice, that could mean £72.43 in interest plus £70 fixed compensation – £142.43 in total , before any further qualifying recovery costs. Whether you actually charge it is also a commercial decision. Sometimes simply making customers aware that statutory charges can be applied is enough to encourage payment. Good credit control starts before the invoice The best way to deal with late payments is, where possible, to stop them becoming late in the first place. That starts when you take on the customer, not 60 days after you've invoiced them. Check new customers before extending significant credit. Companies House can provide useful information, as can proportionate credit checks. For larger contracts, you might also ask for a customer's full statutory accounts rather than relying solely on what's publicly available. Think about your exposure too. If a customer paid you one or two months late, could your business comfortably absorb it? Agree payment terms before starting work and make sure the customer has accepted them. Find out how their payment system works too, particularly with larger organisations where purchase orders, supplier registration, invoice portals and internal approval processes can all cause delays. Then invoice promptly and accurately . Waiting ten days to raise an invoice effectively gives your customer another ten days' credit. Make it easy to pay, use automated reminders where appropriate and don't be afraid to pick up the phone when something becomes overdue. A conversation can often uncover an approval problem or genuine dispute much faster than another automated email. Most importantly, have an escalation process. Decide when a reminder becomes a phone call, when further credit is suspended and when formal recovery action begins. "It's fine, they always pay eventually" isn't much comfort when the outstanding balance has quietly grown to a level your business can't afford. Check how larger customers actually pay If you're considering giving significant credit to a larger company, there's useful information available before you agree their terms. Large companies and LLPs falling within the reporting requirements must publish information about their payment practices at least twice a year. Current size tests include businesses meeting at least two of these thresholds: £54m turnover, £27m balance-sheet total and 250 employees . The published information can show how quickly a business normally pays, including the proportion of invoices paid within 30 days, between 31 and 60 days and after 60 days, as well as how many were paid later than the agreed terms. That's useful information when a prospective customer asks you for generous credit terms. The Fair Payment Code The old Prompt Payment Code has been replaced by the Fair Payment Code , administered by the Office of the Small Business Commissioner. There are three award levels. Gold requires at least 95% of all invoices to be paid within 30 days. Silver requires at least 95% to be paid within 60 days, including at least 95% of invoices to small businesses with fewer than 50 employees within 30 days. Bronze requires at least 95% of all invoices to be paid within 60 days. An award isn't a replacement for doing your own checks, but it can provide another useful indication of how a prospective customer treats its suppliers. What if an invoice is already overdue? Start by finding out why. Check that the customer received the invoice and has everything they need. Has it been approved? Is there a genuine dispute? When is payment actually scheduled? If the customer accepts the debt but is struggling financially, a written payment plan can sometimes achieve a better result than immediately reaching for legal action. Make sure any agreement clearly sets out the amounts and payment dates. If normal chasing gets you nowhere, you can move to a formal demand setting out the amount owed, original due date, any interest or recovery costs and a deadline for payment. Before starting court proceedings, consider the value of the debt, likely recovery costs and whether the customer can actually pay. Winning a court case doesn't magically produce money if the customer is insolvent. Help from the Small Business Commissioner The Office of the Small Business Commissioner provides free support to small UK businesses experiencing payment problems with larger private-sector customers. For its existing complaint service, a small business is one with fewer than 50 employees . In qualifying cases, the Commissioner can provide guidance, contact the larger customer and investigate an unresolved payment dispute. It's generally worth contacting the Commissioner before commencing court proceedings, as they may no longer be able to assist once legal action has started. Keep an eye on your debtors Credit control should be part of your normal financial management, not something you suddenly think about when the bank balance gets uncomfortable. Review your aged-debtor report regularly. Look at what's current, 30 days overdue, 60 days overdue and beyond. Changes in payment behaviour can provide an early warning that a customer is struggling. Your cashflow forecast should also reflect what happens in reality. If your biggest customer is contractually supposed to pay in 30 days but consistently pays in 45, forecasting the cash arriving on day 30 isn't particularly helpful. And remember: turnover isn't cash . Increasing sales can look great in the accounts, but if you're giving customers lengthy credit terms, rapid growth can actually increase pressure on working capital. Don't forget the VAT Late payment can create another headache if you're VAT registered. Under standard VAT accounting, you normally account for VAT based on your sales and purchase invoices even if your customer hasn't paid you yet. You can therefore find yourself paying HMRC VAT on money you haven't actually received. Eligible businesses can consider the VAT Cash Accounting Scheme, where VAT on sales is generally paid when customers pay you. For 2026/27 , businesses can generally join if estimated VAT-taxable turnover for the next 12 months is £1.35m or less , and normally have to leave if VAT-taxable turnover rises above £1.6m . There is a trade-off: input VAT is also normally reclaimed when you pay suppliers rather than when their invoices arrive, so the scheme won't suit everybody. If you've already accounted for VAT and a debt later becomes irrecoverable, VAT bad debt relief may be available. Among the conditions, the debt normally needs to have remained unpaid for at least six months after the later of the payment due date and date of supply, and it must have been written off in your VAT records. Claims generally need to be made within four years and six months of the later of those dates. The late-payment rules are changing There's another reason to keep an eye on this area. The Commercial Payments Bill was introduced in May 2026. As at 7 August 2026 , it had completed committee stage in the House of Lords but had not become law, with its report stage still to be scheduled. Current proposals include a firm maximum payment period of 60 days for many business-to-business contracts, subject to limited exemptions. The Government has indicated that this would begin no earlier than 2027. Possible exemptions include arrangements where both parties are large businesses, where the purchaser is the smaller party, and certain imports and exports. The Bill would also make statutory late-payment interest mandatory, strengthen the Small Business Commissioner's enforcement and dispute-resolution powers, and introduce greater scrutiny of poor payment behaviour by large businesses. For now, these are proposals rather than the current rules . Businesses will need to revisit their contracts and credit-control processes once the legislation receives Royal Assent and implementation dates are confirmed. Getting paid is part of running the business Late payment can't always be avoided, but you can reduce the risk. Clear terms, sensible credit limits, prompt invoices, regular debtor reviews and consistent chasing all help. And if an invoice does become overdue, understanding your rights around interest, compensation and recovery gives you more options. Most importantly, don't wait until an invoice is 60 or 90 days overdue before thinking about credit control. Getting the work is only half the job. Getting paid for it matters too. If you need help improving your cashflow, managing late payments or getting better visibility over your business finances, get in touch.
Student loan interest rates are changing again, with borrowers across every repayment plan seeing an increase from September 2026. The new rates, confirmed by the Department for Education (DfE), will apply from 1 September 2026 to 31 August 2027. There is some protection for borrowers on Plans 2 and 3, however, with the Government retaining a 6% cap which prevents the maximum rate reaching 7.1%. For Plan 1 borrowers , generally those who started undergraduate courses between 1998 and 2012, the interest rate will rise to 4.1%, based on the retail prices index (RPI). That compares with 3.2% in 2025/26, although it remains slightly below the 4.3% charged in 2024/25. Those on Plan 2 , broadly covering undergraduates who started courses between 2012 and 2023, will pay interest of between 4.1% and 6%, depending on their income. Without the Government cap, the maximum rate would have increased to 7.1%. For comparison, the maximum was 6.2% in 2025/26 and 7.3% in 2024/25. Plan 3 postgraduate borrowers will also pay 6%. Again, the cap prevents the rate reaching 7.1%, compared with rates of 6.2% last year and 7.3% the year before. Finally, Plan 5 applies to borrowers who began undergraduate courses in 2023 or later. Their interest rate will increase from 3.2% to 4.1% for 2026/27, still slightly below the 4.3% charged in 2024/25. Of course, student loans don't work in quite the same way as conventional borrowing. What you actually repay is determined by the rules and income thresholds for your particular plan, rather than simply by the size of the outstanding balance. Nevertheless, with rates increasing across the board, it is worth knowing which plan you're on and understanding how the system affects your wider finances – particularly if you're considering whether making additional repayments makes sense. Not sure how your student loan fits into the bigger financial picture? Get in touch and we can talk through the numbers.
Tax receipts rise as HMRC invests further in compliance, data and automation HMRC collected £938.8 billion in tax and National Insurance receipts during 2025/26 , an increase of 9.3% on the previous year . It’s a sizeable figure, but HMRC’s latest annual report tells us more than simply how much tax was collected. It also gives an indication of where the department is heading, particularly when it comes to compliance, digital services and the increasing use of data and automation. For individuals and businesses, those developments are worth paying attention to. Where is the money coming from? Income Tax, Capital Gains Tax and National Insurance remained the biggest sources of Government tax revenue. Together, they accounted for 59% of HMRC’s total receipts during the year, underlining just how important employment and personal taxation remain to the public finances. Alongside collecting tax, HMRC continued to administer tax reliefs, repayments and financial support for individuals and businesses. It also remained responsible for customs processes and supporting international trade. Greater focus on compliance Reducing the tax gap – the difference between the amount of tax theoretically owed and the amount actually collected – remains one of HMRC’s main priorities. During the year, HMRC continued using compliance investigations, debt collection and targeted enforcement to identify and recover unpaid tax. Technology is playing an increasingly important role here too. HMRC continued investing in data, automation and technology to help identify unpaid tax and make its compliance work more efficient. For taxpayers and businesses, good record-keeping has always mattered. As HMRC becomes increasingly capable of analysing and comparing the information available to it, keeping accurate and consistent records becomes even more important. HMRC continues to move online Modernisation was another major theme during 2025/26. HMRC progressed its preparations for Making Tax Digital for Income Tax , while continuing to develop digital services for taxpayers, businesses and agents. The department also wants more routine enquiries to be dealt with online, reducing reliance on telephone support. Customer service performance remained under pressure during the year, although HMRC reported further improvements across its digital channels. Automation and artificial intelligence are also now being used within some of HMRC’s operational and compliance processes. What does this mean for taxpayers? HMRC identified three main priorities during the year: reducing the tax gap, improving customer experience and modernising the tax and customs system . Those objectives shaped both its spending plans and its operational work. For businesses in particular, the direction of travel is fairly clear. Tax administration is becoming increasingly digital and data-led, while HMRC continues to invest in its ability to identify discrepancies and unpaid tax. That doesn't mean businesses need to be worried about HMRC. It does mean there is increasingly little room for poor records, missed deadlines or figures that don't properly reconcile. Final thoughts HMRC's £938.8bn of receipts may be the headline figure, but the wider story in its annual report is how tax administration itself continues to change. Better use of data, greater automation, Making Tax Digital and increased compliance activity are all becoming part of the normal tax environment. For business owners, having good systems and keeping on top of your tax position throughout the year is becoming more important, not less. If you're not confident that your records, tax planning or accounting systems are keeping pace, that's something I can help with. Talk to us about your taxes.
How divorce can affect property, pensions, investments and future tax bills. Divorce or the end of a civil partnership is never just about paperwork. There are often some difficult personal and financial decisions to make, and understandably, tax probably isn’t the first thing on your mind. However, it is something that needs to be considered before a financial settlement is agreed. A division of assets can look perfectly fair on paper, but the after-tax position may tell a different story. One person might receive an investment carrying a significant built-in gain, move out of the family home, take on a property and its mortgage, receive a share of a pension or become responsible for claiming Child Benefit. All of these can have tax consequences. The important thing is to understand those consequences before you sign a settlement and move the assets , rather than discovering them afterwards. To put the subject into context, the latest Office for National Statistics release reported 103,816 legal partnership dissolutions in England and Wales in 2023 , comprising 102,678 divorces and 1,138 civil partnership dissolutions. Divorce rates were 8.6 for men and 8.5 for women per 1,000 married individuals. Timing can make a big difference One of the first things I would establish is the timeline. For tax purposes, seemingly simple dates can make a considerable difference, including when you stopped living together, whether the separation was likely to be permanent, when the conditional order or decree nisi was made, when the final order or decree absolute was made, when a financial agreement or consent order was approved, when assets were transferred or sold, and when somebody moved out of the family home. These dates can affect Capital Gains Tax (CGT), property tax, pensions, Child Benefit, Marriage Allowance and Inheritance Tax planning. For CGT purposes, HMRC treats spouses and civil partners as living together unless they are separated under a court order, by a formal deed of separation, or in circumstances where the separation is likely to be permanent. Simply living in different houses does not automatically mean you are separated for these rules if the marriage or civil partnership has not broken down. Capital Gains Tax and transferring assets CGT is one of the main areas I would look at during a divorce. While spouses or civil partners are living together, transfers of most assets between them generally take place on a “no gain/no loss” basis. In simple terms, the person transferring the asset does not trigger an immediate CGT charge. Instead, the person receiving it effectively takes over the original base cost for future tax purposes. The current separation rules first applied to disposals made on or after 6 April 2023 and give separating couples a longer period in which assets can be transferred on this basis. If you and your spouse or civil partner were living together at some point during a tax year, assets can be transferred on a no gain/no loss basis until the earlier of: The end of the third tax year following the tax year in which you stopped living together; or The date the court grants a divorce, annulment or dissolution. Importantly, transfers made under a formal divorce or separation agreement or court order can qualify for no gain/no loss treatment without a time limit . This is why the legal documentation surrounding a settlement can be so important. Don't just look at the family home The family home understandably gets a lot of attention, but it isn't the only asset that may have a future tax liability attached to it. Buy-to-let properties, second homes, shares, investment portfolios, cryptocurrency, business shares, commercial property, land, valuable personal possessions and overseas assets may all need reviewing. Someone receiving an asset under the no gain/no loss rules might not pay tax when they receive it, but they can inherit its original tax base cost. If they later sell it, CGT may therefore be calculated on the gain since the original purchase , rather than simply the increase in value since the divorce. For 2026/27 , the CGT annual exempt amount for individuals is £3,000 . For gains made from 6 April 2026 , basic rate taxpayers pay CGT at 18% on gains within the basic rate band and 24% on gains above it. Trustees and personal representatives pay CGT at 24% from 6 April 2026. This is why I would always encourage somebody to compare assets on an after-tax basis . £200,000 in cash and an investment portfolio valued at £200,000 are not necessarily worth the same amount if that portfolio contains a substantial unrealised gain. What happens to the family home? The family home is often the largest asset involved and can also be one of the more complicated tax areas. Private Residence Relief can reduce or eliminate CGT when you sell a property that has been your only or main residence. For spouses and civil partners living together, there can only be one main residence between them for the purposes of the relief. After separation, each person may have a different only or main residence. Where somebody moves out of the matrimonial or civil partnership home and later sells or transfers their share, they may be entitled to Private Residence Relief for the period before they moved out, plus the final nine months of ownership . There are also special rules where somebody retains an interest in the former family home and it is eventually sold under a formal divorce or separation agreement or court order. In some circumstances, the person who moved out can choose to treat the period after leaving as though the property remained their only or main residence, provided the necessary conditions are met. However, making that choice can affect the relief available on another home bought after moving out, so this is something I would want reviewed before the property is sold. Stamp Duty Land Tax and mortgages For properties in England and Northern Ireland, Stamp Duty Land Tax (SDLT) does not apply where an interest in land or property is transferred to a spouse or civil partner as part of an agreement or court order because the couple are divorcing, dissolving a civil partnership, annulling a marriage or legally separating. In those circumstances, HMRC does not need to be told about the transfer, even where the value exceeds the SDLT threshold. This is different from certain other property transfers. For example, unmarried joint owners transferring a larger share of a property between themselves can potentially have an SDLT liability where money changes hands or mortgage debt is taken over. Wales and Scotland also have their own systems - Land Transaction Tax in Wales and Land and Buildings Transaction Tax in Scotland - so the position should always be checked according to where the property is located. The mortgage needs considering too. If one person is keeping the family home and taking over the mortgage, the lender will usually need to agree. Outside the special divorce and separation rules, taking responsibility for mortgage debt can also count as chargeable consideration for SDLT purposes. Before agreeing that one person keeps the property, I would therefore want to know whether the lender will release the other person, whether the transfer falls within the divorce or separation SDLT rules, whether either person retains an interest in the property and whether a future sale could result in CGT. I'd also want to know whether the person moving out intends to buy another property. Don't overlook pensions Pensions can be one of the most valuable assets within a marriage, but because you can't necessarily see or access the money today, they're also very easy to undervalue. A pension sharing order can give one person a percentage of the value of their former spouse or civil partner's pension rights. The reduction in the original member's rights is known as the pension debit , while the amount allocated to the former spouse or civil partner is the pension credit . This isn't simply money handed over as cash. The recipient becomes entitled to pension benefits in their own right, with those benefits taxable in their hands when eventually taken, depending on the pension scheme and how they access it. Pensions therefore need to be considered alongside tax, retirement plans, age, health, income requirements and the type of scheme involved. Defined benefit pensions, public sector pensions and pensions already in payment may require specialist advice. Maintenance payments Child maintenance payments are not taxable for the recipient and do not affect benefits, including Universal Credit. Spousal maintenance is different, although most modern divorce maintenance arrangements don't provide a straightforward tax deduction for the person making the payments. A limited Maintenance Payments Relief still exists where specific conditions are satisfied, including that either person was born before 6 April 1935 . For 2026/27 , this relief is worth 10% of qualifying maintenance payments, up to a maximum tax reduction of £453 . Where maintenance forms part of a settlement, both parties should therefore understand how it affects their wider tax and cash-flow position. Child Benefit can change after separation If children are involved, Child Benefit should also be reviewed. For 2026/27 , Child Benefit is £27.05 per week for the eldest or only child and £17.90 per week for each additional child. The High Income Child Benefit Charge applies where the higher earner in a couple has adjusted net income above £60,000 . It is based on that person's individual income rather than the couple's combined income. The charge gradually claws back Child Benefit between £60,000 and £80,000 , with the full Child Benefit amount being clawed back once adjusted net income exceeds £80,000 . Following a permanent separation, the former partner's income is no longer taken into account. The threshold instead applies to the parent receiving Child Benefit or their new partner, where applicable. Separation can therefore change who should claim, who might become liable for the charge and who receives valuable National Insurance credits. Marriage Allowance and tax codes Marriage Allowance allows eligible married couples and civil partners to transfer £1,260 of one person's Personal Allowance to the other. For 2026/27 , the standard Personal Allowance is £12,570 , and the transfer can reduce the receiving partner's tax bill by up to £252 . Marriage Allowance must be cancelled where the relationship ends through divorce, dissolution of a civil partnership or legal separation. Tax codes may also need updating following changes to somebody's name, address, employment benefits or taxable income. It's a relatively small administrative point, but one that can easily get forgotten when there are much bigger things going on. Inheritance Tax, wills and estate planning Divorce can have a significant effect on estate planning. Transfers between spouses and civil partners are generally exempt from Inheritance Tax while the marriage or civil partnership continues, but that position changes following divorce or dissolution. Existing wills should also be reviewed because divorce can affect how their provisions operate. For 2026/27 , the Inheritance Tax nil rate band is £325,000 and the residence nil rate band is £175,000 . The residence nil rate band is available where a qualifying residence passes to direct descendants, subject to the relevant conditions, and the taper begins where the net estate exceeds £2 million . HMRC states that qualifying estates can continue to pass on up to £500,000 , or up to £1 million for a surviving spouse or civil partner where the relevant unused allowances are available. After a separation, I would recommend reviewing your will, pension death benefit nominations, life insurance policies, jointly owned property, trusts, guardianship wishes for children and any powers of attorney. Tax planning and legal planning really need to work together here. What if you own a business together? Where one or both spouses own a business, there can be another layer of complexity. You may need to consider whether shares are being transferred, whether no gain/no loss CGT treatment applies, the company's distributable reserves, changes to dividends, whether both people remain directors or employees, whether one person is exiting the business, whether a valuation is required and the terms of any shareholder agreement. Dividend tax rates changed for 2026/27 . The dividend allowance remains £500 , while the dividend tax rates are 10.75% for basic rate taxpayers, 35.75% for higher rate taxpayers and 39.35% for additional rate taxpayers . If company shares form part of a divorce settlement, I would always recommend reviewing the position before anything is signed. The legal value of those shares, their tax base cost, future dividend rights and the control they provide aren't necessarily the same thing. A note for unmarried couples Many of the special tax rules I've discussed apply specifically to spouses and civil partners. Unmarried couples should therefore take particular care because the tax treatment can be very different, particularly for CGT, SDLT, Inheritance Tax and pensions. For example, where unmarried joint owners transfer an interest in a property from one owner to another, there can be an SDLT position if consideration is given, including taking over mortgage debt. Living together does not automatically provide the same tax treatment as marriage or civil partnership. Before agreeing a settlement There is quite a lot to consider, which is exactly why I wouldn't leave the tax review until after an agreement has been reached. Before finalising a divorce or dissolution settlement, I would want to establish what each person owns, whether any assets contain built-in gains, whether transfers qualify for no gain/no loss CGT treatment, and what happens to the family home. I'd also look at mortgages, pensions, maintenance, Child Benefit, the High Income Child Benefit Charge, Marriage Allowance, tax codes, wills and pension nominations, as well as any business shares or company income involved. Summing up Tax planning during a divorce isn't about making a settlement less fair. Quite the opposite – it's about understanding what each person is actually receiving once tax is taken into account . Two assets with exactly the same value on paper can leave their owners in very different financial positions. Timing, ownership, residence history and future plans can all change the outcome, particularly where property, pensions, investments, businesses or Child Benefit are involved. The best time to review all of this is before the financial order is finalised and before assets are transferred . That way, everyone has a clearer picture of the real after-tax position and there is less chance of an unexpected tax bill appearing further down the line. If you're going through a divorce or separation and would like help understanding how property, pensions, investments or Child Benefit could affect your tax position, please get in touch.
According to the Department for Work and Pensions’ (DWP) latest annual report and accounts, fraudulent benefit overpayments reached £9.9 billion in 2025/26 , up from £9.4bn the previous year. Interestingly, that increase doesn’t mean the overall rate of overpayment has gone up. In fact, the rate of benefit spending lost through fraud and error actually fell slightly, from 3.3% to 3.2% . The cash figure has increased because the Government is spending more on benefits overall. Universal Credit still accounts for the largest amount Universal Credit remains responsible for by far the biggest share of overpayments. Its overpayment rate fell from 9.5% to 8.5% , but again the amount of money involved went in the opposite direction, increasing from £6.2bn to £6.7bn . There was better news for Housing Benefit, where both figures fell. The overpayment rate dropped from 7.2% to 6.2% , while the amount overpaid reduced from £1.1bn to £800 million . PIP overpayments almost double One of the more striking figures is for Personal Independence Payment (PIP). Overpayments almost doubled from £330m to £660m , with the overpayment rate rising from 1.3% to 2.3% . The figures come alongside the Government's review of the PIP system, which concluded that the current approach is no longer fit for purpose. Pension Credit, meanwhile, had the highest overpayment rate of any benefit at 10% , equivalent to £620m. That compares with 10.3%, or £610m, a year earlier. State Pension overpayments also increased, rising from £180m to £230m . What is the DWP doing about it? The DWP says its counter-fraud work prevented around £27bn of incorrect payments during 2025/26. It also reviewed 1.2 million Universal Credit claims , identifying and correcting around 250,000 awards . The department estimates that work alone generated savings of approximately £1.1bn . Its longer-term target is to bring the overall level of fraud and error across the welfare system down to 2.8% by 2028/29 . There are a lot of very large numbers here, but the distinction between the percentage rate and the actual amount being lost is important. While the overall overpayment rate has edged down, increasing benefit expenditure means the cost to the public purse has still risen. Whether the measures now being taken can reverse that trend remains to be seen. Talk to us about your finances.
The UK’s crypto industry has reached what the Financial Conduct Authority (FCA) describes as a “significant milestone”, with the timetable now set for a much wider regulatory regime. From October 2027, crypto firms operating in the UK will need to meet tougher standards around financial resilience, market integrity and consumer protection. The new regime will cover trading platforms, intermediaries, custodians, stablecoin issuers and firms arranging staking. Importantly, firms carrying out these activities will need FCA authorisation to operate in the UK. There is some time to prepare. Applications will open on 30 September 2026 and close on 28 February 2027, ahead of the new rules becoming mandatory from October 2027. The FCA says the measures follow a series of consultations with the industry, with changes made to ensure the regime works in practice rather than simply adding another layer of regulation. For example, capital requirements for stablecoin firms have been simplified, while trading rules have been adapted to better reflect the way crypto markets actually operate. Stablecoins themselves will also come under clearer standards. These are crypto assets designed to maintain a stable value, usually by being linked to a currency such as sterling or the US dollar. The FCA believes clearer rules should help build trust in how stablecoins are used over time. Another significant area is market abuse. The new regime will introduce rules covering issues such as insider dealing and market manipulation, alongside further guidance on inside information, legitimate market practice, best execution and how firms should monitor trading activity. Businesses safeguarding qualifying crypto assets will also face dedicated client asset rules, reflecting the particular risks involved in holding these assets on behalf of customers. For now, however, the FCA’s oversight of the crypto sector remains relatively limited, covering financial promotions and anti-money laundering controls until October 2027. There’s clearly still some way to go before the full regime takes effect, but for businesses operating in the crypto sector, the direction of travel is now much clearer. With the application window opening in September 2026, firms affected by the changes should be thinking about what the new requirements will mean for them well before the October 2027 deadline. Need to talk through what changes affecting your business could mean for your finances? Get in touch.
E-invoicing is coming – but what does that actually mean for your business? E-invoicing is going to become mandatory for all UK VAT invoices from April 2029. Now, 2029 might sound comfortably far away. And no, I’m certainly not suggesting businesses need to start ripping out their accounting systems tomorrow. But this is one of those changes where understanding what’s coming – and making sure your current processes aren’t going to cause problems later – is probably rather sensible. Particularly because e-invoicing isn’t simply about emailing invoices instead of putting them in the post. A PDF isn’t an e-invoice This is probably the first important distinction. Lots of businesses already consider their invoicing to be digital. They raise an invoice in their accounting software, turn it into a PDF and email it to the customer. But that isn’t what HMRC means by e-invoicing. An e-invoice involves invoice data being exchanged digitally and directly between the supplier’s and customer’s finance systems, even where they use different software. Rather than somebody receiving a PDF and then checking, coding, approving or entering the information, the structured data can feed directly into their system. That includes things such as supplier details, VAT numbers, invoice dates, tax points, purchase order references, VAT rates and payment terms. In other words, the invoice doesn’t just look digital. The information behind it is digital too. So, what’s actually changing? The government has confirmed that e-invoicing will become mandatory for all VAT invoices from April 2029. That generally means business-to-business and business-to-government transactions where VAT is due, rather than your normal business-to-consumer retail transactions. We don’t yet have all the detail. HMRC and the Department for Business and Trade are due to publish an implementation roadmap at Budget 2026, which should give us more information about the timetable, staging, standards and practical requirements. We do know, however, that Peppol has been announced as the UK’s core interoperability network for e-invoicing. So the direction of travel is becoming considerably clearer. Another step towards digital tax This shouldn’t really come as a huge surprise. VAT-registered businesses are already required to maintain digital VAT records and submit their returns through Making Tax Digital software. For 2026/27, the VAT registration threshold remains £90,000, with the deregistration threshold at £88,000. The standard VAT rate remains 20%, alongside the reduced rate of 5% and zero rate of 0%. Making Tax Digital for Income Tax has also now started for sole traders and landlords with qualifying income over £50,000 from 6 April 2026. That threshold falls to £30,000 from 6 April 2027 and £20,000 from 6 April 2028. E-invoicing is another part of that same general move towards structured digital records, more regular reporting and less manual data entry. But 2029 is ages away… True. And businesses certainly don’t need to complete an e-invoicing rollout now. But there’s a fairly big gap between businesses thinking they invoice digitally and actually being ready for e-invoicing. HMRC-commissioned research found that 59% of VAT-registered SMEs surveyed were familiar with the definition of e-invoicing, but only 29% said they actually used it. PDF and email remained the most common ways of sending and receiving invoices, followed by good old-fashioned paper and post. So there’s potentially quite a bit of work to be done. And some businesses may find they need to make changes well before April 2029. Larger businesses and public sector organisations could start requiring suppliers to provide structured or Peppol-ready invoices as part of their own preparations. If one of those organisations happens to be a major customer, their timetable may suddenly become rather more important than the government’s. This isn’t really just about software There’s a temptation with anything involving the word “digital” to assume the answer is simply buying or upgrading some software. It isn’t. E-invoicing touches the whole process – sales invoices, purchase invoices, customer and supplier information, VAT coding, purchase orders, approvals, credit control and ultimately getting paid. So a useful starting point is simply to look at how invoices currently travel through your business. How are sales invoices created and checked? Are the correct customer details and VAT information held? Are purchase order numbers regularly missing? How quickly do invoices actually go out? And on the other side, how do supplier invoices arrive? Who approves them? How is the VAT checked? Are credit notes dealt with properly? Is somebody manually entering information that already exists somewhere else? Those are process questions rather than technology questions. Your data matters too Structured invoicing relies on structured – and accurate – information. Customer and supplier records therefore become rather important. Legal and trading names, addresses, VAT and company registration numbers, finance contacts, purchase order requirements, payment terms and bank details all need to be right. VAT numbers are an obvious area to pay particular attention to. At the moment, a human being can often spot that something is slightly wrong and work around it. Automated systems tend to be rather less forgiving and are more likely to reject or flag information that doesn’t meet the required format. Cleaning up that information now isn't wasted effort anyway. Good data makes your current accounting processes better too. And then there’s cashflow This is perhaps where e-invoicing becomes more interesting than simply another compliance exercise. Late payment remains a huge problem for UK businesses. The government’s late payment response estimated that late payments cost the UK economy almost £11 billion each year, with around 14,000 businesses closing annually as a result. At any given time, businesses are estimated to be owed around £26 billion in late payments. E-invoicing obviously isn’t going to magically make a customer who doesn’t want to pay suddenly reach for their bank card. But it can remove some of the excuses and delays. Missing purchase order numbers, incorrect information, invoices sitting waiting to be entered onto a system and unclear approval processes can all delay payment. If businesses use the move to e-invoicing as an opportunity to improve those processes, there could be a genuine commercial benefit alongside the compliance one. What should businesses do now? For most businesses, I wouldn't be recommending dramatic changes at this stage. But I would be asking a few questions. Does your current accounting software support structured e-invoicing, or is it planning to? What about Peppol? Does it handle purchase orders, approvals and credit notes properly? Does it integrate with the other systems you use? And perhaps more importantly, where are the manual bits in your current process? Spreadsheets, PDFs, paper invoices, email approvals and manually rekeying information aren't necessarily problems today. But knowing where you rely on them gives you a much better idea of what may eventually need to change. It's also worth looking at your larger customers, public sector customers and overseas customers. They may well start introducing their own e-invoicing requirements before the UK deadline arrives. And don't forget purchase invoices. Receiving structured supplier invoices can reduce manual entry, improve VAT coding, speed up approvals and give businesses better visibility over what they owe. So this isn't only about how you send invoices to customers. What happens next? The next important milestone will be the Budget 2026 roadmap. That should tell us more about the detailed timetable, whether there will be any phasing by business size or transaction type, Peppol and technical requirements, transitional arrangements, legacy software and the support available to smaller businesses. The government has already said it will continue talking to stakeholders about older systems that can't interoperate with the future system. That could be particularly important for businesses using bespoke, older or sector-specific software. Once we have the roadmap, businesses should be in a much better position to work out what – if anything – they actually need to change. For now, don't panic – but don't ignore it either April 2029 is still some way off. There's no need to rush into changing perfectly good software or completely redesigning your invoicing process simply because e-invoicing is coming. But there is an opportunity here. Businesses can use the next couple of years to tidy their customer and supplier data, understand where manual work exists, talk to their software providers and improve the processes around invoicing and payment. Then, when the detailed requirements become clearer, they'll be making planned decisions rather than hurried ones. And if the end result is less admin, fewer invoice errors, quicker approvals and better cashflow, e-invoicing might turn out to be more than simply another HMRC compliance requirement.
Millions of homeowners could see their mortgage repayments increase over the next few years, according to the latest forecasts from the Bank of England. Its latest Financial Stability Report suggests that more than 5 million homeowners are expected to face higher monthly repayments by the end of 2028 . That's one million more than the Bank predicted in December, with the change linked to the economic impact of the Iran conflict and higher energy prices. What could this mean for borrowers? The good news is that, for many people, the increases are expected to be more modest than those seen over the past couple of years. The Bank estimates that a typical homeowner coming to the end of a fixed-rate mortgage over the next two years will pay around £45 more per month . That compares with borrowers who refinanced between late 2022 and the end of 2024, when average repayments increased by around £120 per month . However, not everyone will see only a small increase. Around 750,000 homeowners currently paying mortgage rates below 3% are due to come off those deals this year. For this group, the Bank expects repayments to rise by an average of £170 per month . Why have expectations changed? Before the recent conflict involving Iran, the outlook had been more positive. More than 2 million borrowers with two-year fixed-rate mortgages ending before the close of 2028 had been expected to remortgage at similar rates, with some even seeing their monthly repayments fall. That picture has now changed. The conflict pushed up oil and gas prices after the closure of the Strait of Hormuz, increasing concerns about inflation and reducing expectations of further interest rate cuts. Mortgage lenders have reflected those higher funding costs in the rates they offer borrowers. Most homeowners are protected... for now More than eight in ten mortgage holders are currently on fixed-rate deals, typically lasting two or five years. That means their monthly repayments won't change until their current deal comes to an end. The challenge comes when it's time to remortgage. For some households, even a relatively modest increase in monthly repayments can make a noticeable difference to the household budget. A practical view No one can predict exactly where mortgage rates will be in the next year or two, but this is a reminder that borrowing costs can change quickly when wider economic events unfold. If your fixed-rate mortgage is due to end over the next 12 to 18 months, it's worth reviewing your finances early rather than waiting until the last minute. Having time to understand your options can make budgeting much easier if repayments are likely to increase. Final thought The latest forecasts suggest that mortgage costs are likely to remain under pressure for many homeowners over the coming years. While the increases are expected to be less severe than those experienced during the recent interest rate rises, they could still have a meaningful impact on household finances. Planning ahead, reviewing your budget and understanding your options before your current deal expires can help avoid unnecessary surprises. If you'd like to discuss how rising mortgage costs fit into your wider financial plans, feel free to get in touch.
Employers are becoming more cautious as confidence weakens Many businesses are taking a more cautious approach to recruitment, with temporary staff increasingly being chosen over permanent hires. A new report from the recruitment industry suggests that uncertainty around the economy, rising costs and wider global events are all influencing hiring decisions, as employers look to remain flexible. For many businesses, it's another sign that confidence remains fragile despite hopes of a stronger year. Permanent recruitment slows According to the latest report, permanent staff appointments fell in May at the fastest rate seen in 10 months . Recruiters say many employers are reluctant to commit to expanding their permanent workforce while economic conditions remain uncertain. Political uncertainty in the UK, together with ongoing conflict in the Middle East, has added to concerns about the wider outlook, making some businesses more cautious about long-term recruitment decisions. The findings are based on a survey of 400 UK recruitment and employment consultancies , carried out during the middle of May. More people looking for work The report also found that more candidates are actively looking for employment. Recruiters suggest this is being driven by a combination of redundancies, fewer vacancies and growing concerns about job security. At the same time, demand from employers has weakened, with many businesses working within tighter budgets. As a result, both starting salaries and temporary pay rates increased only modestly during May compared with the previous month. Some sectors remain stronger than others Not every industry is seeing the same picture. The nursing, medical and care sector was the only area monitored by the report to record an increase in demand for permanent staff. By contrast, retail experienced the sharpest fall in permanent vacancies, highlighting the continued pressures facing many consumer-facing businesses. A wider picture of the labour market The recruitment data adds to other recent signs that the UK labour market is becoming more challenging. Official figures recently showed the unemployment rate rising unexpectedly to 5% in the three months to March, while wage growth has also begun to slow. The report follows separate Government-backed research which found that more than one million young people are now not in work or education - the highest level for more than a decade. Together, these figures suggest many employers are taking a more measured approach to recruitment while they wait for greater economic certainty. Final thoughts Recruitment is rarely a one-size-fits-all decision. While wider economic trends are worth keeping an eye on, the right approach will depend on your own business, your cashflow and your plans for growth. For some businesses, taking on permanent staff will still be the right move. For others, temporary or flexible arrangements may provide the breathing space needed while trading conditions remain uncertain. Having a clear understanding of your finances can make those decisions much easier and help ensure you're planning from a position of confidence rather than reacting to headlines. Talk to us about your business.
Protecting your corporation tax thresholds Running more than one limited company is common for many owner-managed businesses. You might have a trading company alongside a property company, a separate company for a different service line, a holding company sitting above the group, or perhaps an older company that's been retained for a particular brand or project. Each company may make perfect commercial sense on its own. The important point is that, for corporation tax purposes, HMRC may look at those companies together. Since 1 April 2023 , the UK has operated a tiered corporation tax system. The thresholds that determine whether a company pays the 19% small profits rate , the 25% main rate , or falls into the marginal relief band between the two can be divided between associated companies. The more associated companies there are, the lower those thresholds become for each company. This guide explains how the rules apply for accounting periods falling within the corporation tax financial year beginning 1 April 2026 , who counts as an associated company, and the practical steps you can take to protect your position. Corporation tax rates For the financial year beginning 1 April 2026 , the corporation tax rates remain: 19% small profits rate for companies with profits up to £50,000 25% main rate for companies with profits over £250,000 Marginal relief for profits between £50,000 and £250,000 The Government's Corporate Tax Roadmap has also confirmed its intention to keep the headline corporation tax rate capped at 25% throughout this Parliament, while retaining the current small profits rate and marginal relief thresholds. One point that's often overlooked is how marginal relief works. Companies within the marginal relief band are first charged corporation tax at 25% , before marginal relief is deducted using the standard 3/200 fraction . In practice, profits within this band can face an effective marginal corporation tax rate of 26.5% . That's why it's important to monitor profit levels carefully. The associated company rules can bring a business into the marginal relief band much sooner than many directors expect. What is an associated company? The rules are based on control . A company is associated with another if: One company controls the other, or Both companies are controlled by the same person or group of people. For accounting periods beginning on or after 1 April 2023 , the corporation tax thresholds are divided by the total number of associated companies, including the company itself. It's also worth remembering that a company can count as associated even if that relationship only exists for part of the accounting period. This often catches people out when companies are formed, sold, struck off or reorganised during the year. For a 12-month accounting period, a standalone company has the full £50,000 lower limit and £250,000 upper limit available. If there are two associated companies , those limits reduce to £25,000 and £125,000 for each company. With three associated companies , they reduce further to approximately £16,667 and £83,333 . With four associated companies , the limits become £12,500 and £62,500 , while five associated companies reduce them again to £10,000 and £50,000 . For example, a standalone company making £40,000 of taxable profit would normally expect to pay corporation tax at 19% . If it has three associated companies, however, its thresholds reduce to £12,500 and £62,500 , meaning that same £40,000 profit could fall into the marginal relief band. Control is wider than many people realise Control isn't limited to share ownership. It can also include voting rights, entitlement to income or assets on a winding up, and rights held indirectly. The rules can also take account of a person's associates , including: A spouse or civil partner Parents, grandparents and other lineal ancestors Children, grandchildren and other lineal descendants Brothers and sisters Business partners Certain trustees and personal representatives That doesn't automatically mean every family-owned company becomes associated. Where companies are controlled by associates, HMRC will consider whether there is substantial commercial interdependence between them. For example, a husband and wife may each own separate businesses in completely different sectors. Those businesses would not usually be associated simply because they are married. However, that position may change if they share customers, staff, premises, funding, equipment or management. What is substantial commercial interdependence? HMRC looks at three broad areas. Financial interdependence This may exist where one company financially supports another, or where both have a financial interest in the same business. Examples include: Inter-company loans Guarantees Shared funding Informal financial support Economic interdependence This looks at whether companies work towards the same commercial objectives. Shared customers, regular referrals or businesses that rely on each other commercially may all indicate economic interdependence. Organisational interdependence Companies may also be linked through shared: Management Employees Premises Equipment Administrative support Systems Not every connection has to exist. A strong link in just one area may be enough, depending on the circumstances. Companies that often catch people out Some of the most common situations include: Old companies retained for future projects or brand names. Property companies renting premises to a trading company. Family companies providing loans, equipment or referrals. Separate companies owned by spouses but sharing staff or administration. Investment companies that appear dormant but still receive investment income. It's also important to distinguish between being dormant at Companies House and being dormant for corporation tax purposes. The two aren't necessarily the same. Similarly, while some passive holding companies can be ignored under specific rules, the conditions are narrow and shouldn't be assumed to apply without checking. Quarterly instalment payments Associated companies don't just affect corporation tax rates. They can also affect when corporation tax has to be paid. A company is normally regarded as large if annual taxable profits exceed £1.5 million but do not exceed £20 million . However, from 1 April 2023 , that £1.5 million threshold is also divided by the number of associated companies. For example, where there are three associated companies in total, the threshold reduces to £500,000 . That can have significant cashflow implications. Large companies generally pay corporation tax in four instalments throughout the accounting period: Six months and 13 days after the start of the accounting period. Three months after the first instalment. Three months after the second instalment. Three months and 14 days after the end of the accounting period. Very large companies, with profits above £20 million (again adjusted for associated companies), pay even earlier. Although exceptions do exist, including where corporation tax is below £10,000 or certain first-year provisions apply, these rules should always be reviewed before payment dates are assumed. Practical steps If you operate more than one company, it's worth reviewing your structure regularly. Good practice includes: Reviewing all connected companies each year. Checking whether older companies are still needed. Keeping transactions between companies on commercial terms. Separating premises, staff, systems and customers wherever possible. Planning profits across the group. Documenting where businesses genuinely operate independently. Final thoughts The associated company rules can affect both how much corporation tax you pay and when you have to pay it . If you run multiple companies, have family members with their own businesses, or are thinking about setting up another company, it's worth reviewing the position before your next year end. A straightforward review can identify which companies count, whether any exclusions apply, and whether you're approaching the marginal relief band or quarterly instalment payment thresholds. If you'd like to review your associated company position before your next year end, I'm always happy to have a conversation. Talk to us about your business.
Guaranteed hours plans move forward: What the proposed employment reforms could mean for businesses The Government has announced further details of its plans to give workers on zero-hours and low-hours contracts greater certainty over their working patterns. The proposals form part of Labour's wider programme of employment reforms and are intended to provide workers with greater security over both their hours and their income. However, while supporters say the changes could improve financial stability for employees, many businesses are concerned about the practical impact, particularly in sectors where staffing needs change throughout the year. What is being proposed? Under the latest proposals, employees who regularly work more hours than their contracted amount could become entitled to a contract that reflects those hours after an initial 12-week reference period . The Government's preferred approach is to give eligible workers a guaranteed baseline of hours, providing more certainty over earnings and making it easier for individuals to budget and plan their finances. The new right would apply not only to people on zero-hours contracts but also to workers on low-hours contracts. Ministers are currently considering defining a low-hours contract as somewhere between eight and 20 hours per week . Why is the Government introducing the changes? The proposals are designed to deliver Labour's commitment to end what it describes as exploitative zero-hours contracts. Supporters argue that workers who regularly work consistent hours should have contracts that better reflect the reality of their working pattern, giving them greater financial security and reducing uncertainty around future income. For many employees, knowing what they are likely to earn each month can make budgeting considerably easier. Questions still remain Although the direction of travel is becoming clearer, several important details have yet to be confirmed. The Government is still consulting on issues including: How guaranteed hours will be calculated. How seasonal or variable work will be treated. What happens once the initial 12-week assessment period has ended. Until those details are finalised, businesses may find it difficult to assess exactly how the proposals could affect their workforce. Concerns from employers Business groups have expressed concerns that the reforms may prove challenging for industries where staffing requirements naturally fluctuate. Sectors such as retail, hospitality and leisure often experience seasonal peaks and quieter trading periods. Employers argue that using a fixed 12-week reference period may not accurately reflect those seasonal patterns and could leave businesses committed to guaranteeing hours that are no longer needed once demand falls. As with many employment reforms, the final detail will determine how significant the impact is in practice. What happens next? The Government's consultation remains open until August , with further detail expected once responses have been reviewed. The proposed Fair Work Agency would have powers to enforce compensation where shifts are cancelled or changed without sufficient notice. However, workers seeking a guaranteed-hours contract would still need to pursue claims through the employment tribunal system. Final thoughts Employment law continues to evolve, and proposals such as these are another reminder that businesses need to keep a close eye on upcoming changes. While the reforms are still subject to consultation, employers who rely on flexible working arrangements may wish to start considering how the proposals could affect workforce planning, contracts and staffing costs. Understanding the potential impact early can make it much easier to adapt if the legislation goes ahead. If you'd like to discuss how these proposed changes could affect your business, please get in touch.
Protecting your corporation tax thresholds Running more than one limited company is common for many owner-managed businesses. You might have a trading company alongside a property company, a separate company for a different service line, a holding company sitting above the group, or perhaps an older company that's been retained for a particular brand or project. Each company may make perfect commercial sense on its own. The important point is that, for corporation tax purposes, HMRC may look at those companies together. Since 1 April 2023 , the UK has operated a tiered corporation tax system. The thresholds that determine whether a company pays the 19% small profits rate , the 25% main rate , or falls into the marginal relief band between the two can be divided between associated companies. The more associated companies there are, the lower those thresholds become for each company. This guide explains how the rules apply for accounting periods falling within the corporation tax financial year beginning 1 April 2026 , who counts as an associated company, and the practical steps you can take to protect your position. Corporation tax rates For the financial year beginning 1 April 2026 , the corporation tax rates remain: 19% small profits rate for companies with profits up to £50,000 25% main rate for companies with profits over £250,000 Marginal relief for profits between £50,000 and £250,000 The Government's Corporate Tax Roadmap has also confirmed its intention to keep the headline corporation tax rate capped at 25% throughout this Parliament, while retaining the current small profits rate and marginal relief thresholds. One point that's often overlooked is how marginal relief works. Companies within the marginal relief band are first charged corporation tax at 25% , before marginal relief is deducted using the standard 3/200 fraction . In practice, profits within this band can face an effective marginal corporation tax rate of 26.5% . That's why it's important to monitor profit levels carefully. The associated company rules can bring a business into the marginal relief band much sooner than many directors expect. What is an associated company? The rules are based on control . A company is associated with another if: One company controls the other, or Both companies are controlled by the same person or group of people. For accounting periods beginning on or after 1 April 2023 , the corporation tax thresholds are divided by the total number of associated companies, including the company itself. It's also worth remembering that a company can count as associated even if that relationship only exists for part of the accounting period. This often catches people out when companies are formed, sold, struck off or reorganised during the year. For a 12-month accounting period, a standalone company has the full £50,000 lower limit and £250,000 upper limit available. If there are two associated companies , those limits reduce to £25,000 and £125,000 for each company. With three associated companies , they reduce further to approximately £16,667 and £83,333 . With four associated companies , the limits become £12,500 and £62,500 , while five associated companies reduce them again to £10,000 and £50,000 . For example, a standalone company making £40,000 of taxable profit would normally expect to pay corporation tax at 19% . If it has three associated companies, however, its thresholds reduce to £12,500 and £62,500 , meaning that same £40,000 profit could fall into the marginal relief band. Control is wider than many people realise Control isn't limited to share ownership. It can also include voting rights, entitlement to income or assets on a winding up, and rights held indirectly. The rules can also take account of a person's associates , including: A spouse or civil partner Parents, grandparents and other lineal ancestors Children, grandchildren and other lineal descendants Brothers and sisters Business partners Certain trustees and personal representatives That doesn't automatically mean every family-owned company becomes associated. Where companies are controlled by associates, HMRC will consider whether there is substantial commercial interdependence between them. For example, a husband and wife may each own separate businesses in completely different sectors. Those businesses would not usually be associated simply because they are married. However, that position may change if they share customers, staff, premises, funding, equipment or management. What is substantial commercial interdependence? HMRC looks at three broad areas. Financial interdependence This may exist where one company financially supports another, or where both have a financial interest in the same business. Examples include: Inter-company loans Guarantees Shared funding Informal financial support Economic interdependence This looks at whether companies work towards the same commercial objectives. Shared customers, regular referrals or businesses that rely on each other commercially may all indicate economic interdependence. Organisational interdependence Companies may also be linked through shared: Management Employees Premises Equipment Administrative support Systems Not every connection has to exist. A strong link in just one area may be enough, depending on the circumstances. Companies that often catch people out Some of the most common situations include: Old companies retained for future projects or brand names. Property companies renting premises to a trading company. Family companies providing loans, equipment or referrals. Separate companies owned by spouses but sharing staff or administration. Investment companies that appear dormant but still receive investment income. It's also important to distinguish between being dormant at Companies House and being dormant for corporation tax purposes. The two aren't necessarily the same. Similarly, while some passive holding companies can be ignored under specific rules, the conditions are narrow and shouldn't be assumed to apply without checking. Quarterly instalment payments Associated companies don't just affect corporation tax rates. They can also affect when corporation tax has to be paid. A company is normally regarded as large if annual taxable profits exceed £1.5 million but do not exceed £20 million . However, from 1 April 2023 , that £1.5 million threshold is also divided by the number of associated companies. For example, where there are three associated companies in total, the threshold reduces to £500,000 . That can have significant cashflow implications. Large companies generally pay corporation tax in four instalments throughout the accounting period: Six months and 13 days after the start of the accounting period. Three months after the first instalment. Three months after the second instalment. Three months and 14 days after the end of the accounting period. Very large companies, with profits above £20 million (again adjusted for associated companies), pay even earlier. Although exceptions do exist, including where corporation tax is below £10,000 or certain first-year provisions apply, these rules should always be reviewed before payment dates are assumed. Practical steps If you operate more than one company, it's worth reviewing your structure regularly. Good practice includes: Reviewing all connected companies each year. Checking whether older companies are still needed. Keeping transactions between companies on commercial terms. Separating premises, staff, systems and customers wherever possible. Planning profits across the group. Documenting where businesses genuinely operate independently. Final thoughts The associated company rules can affect both how much corporation tax you pay and when you have to pay it . If you run multiple companies, have family members with their own businesses, or are thinking about setting up another company, it's worth reviewing the position before your next year end. A straightforward review can identify which companies count, whether any exclusions apply, and whether you're approaching the marginal relief band or quarterly instalment payment thresholds. If you'd like to review your associated company position before your next year end, I'm always happy to have a conversation. Talk to us about your business.
More people may be falling short of the retirement they expect A new report from Pensions UK suggests that too many people are heading towards a significant drop in income when they retire, with most unlikely to have saved enough to maintain what is considered a moderate standard of living. According to the report, a moderate retirement lifestyle now requires an annual income of £32,700 for a single person and £45,400 for a couple . However, only 23% of working-age people are currently on track to reach that level. The findings highlight the growing challenge of retirement planning as the cost of living continues to increase. What does retirement really cost? Pensions UK estimates that the income needed to achieve different standards of living has continued to rise. A minimum retirement income is now estimated at: £13,900 a year for a single person £22,500 a year for a couple The report suggests that around 82% of workers are on course to achieve this level. For those hoping to enjoy a more comfortable retirement , the figures are considerably higher: £45,400 a year for an individual £62,700 a year for a couple Only 9% of workers are currently expected to reach that standard. Why are the figures increasing? The retirement income calculations are based on the independently developed Retirement Living Standards produced by the Centre for Research in Social Policy at Loughborough University. They are designed to reflect the cost of everyday life in retirement, including spending on food, transport, leisure activities and holidays. Housing costs are excluded from the calculations. According to Pensions UK, higher spending on food and social activities has pushed retirement costs higher over the past year, broadly in line with inflation. A growing focus on retirement planning The report has prompted renewed calls for workers, employers and the Government to do more to improve retirement savings. It also comes as the Government has revived the Pension Commission, which previously led to the introduction of automatic enrolment into workplace pensions. While automatic enrolment has encouraged millions more people to save for retirement, the latest figures suggest that, for many, current contribution levels may not be enough to achieve the lifestyle they hope for later in life. Final thoughts Retirement can feel a long way off, particularly when you're focused on the day-to-day demands of work and family life. However, small decisions made today can have a significant impact over the long term. Whether you're employed, self-employed or running your own business, it's worth reviewing your retirement plans regularly to make sure your savings remain on track and continue to reflect your future goals. If you'd like to discuss your finances or how pensions fit into your wider financial planning, I'm always happy to have a straightforward conversation. Talk to us about your savings.
Rising repayments continue to affect affordability Higher borrowing costs are continuing to put pressure on homebuyers, with many now spending the largest share of their income on mortgage repayments since the 2008 financial crisis. New analysis from UK Finance, the trade body for the banking and finance industry, shows that buyers are now spending an average of 21.3% of their gross household income on their initial mortgage repayments. As borrowing becomes more expensive, affordability is becoming an increasing challenge for many households, reducing demand in parts of the UK housing market. Some areas are feeling the pressure more than others The impact isn't being felt equally across the country. Areas including East Anglia and parts of London's commuter belt remain among the least affordable, where higher property prices continue to combine with elevated mortgage costs. According to the figures, North Norfolk is currently the least affordable local authority, with borrowers spending 25.7% of their gross income on mortgage repayments. It is followed by: Hillingdon – 25.1% Luton – 24.9% Slough – 24.8% Spelthorne – 24.8% These figures highlight how location continues to play a significant role in housing affordability. Confidence remains under pressure The latest data comes against a backdrop of higher interest rates and continued economic uncertainty, both of which are influencing buying decisions. For many prospective buyers, higher monthly repayments mean delaying a move, reducing their budget or stepping back from the market altogether until conditions improve. According to reports in The Negotiator, house prices also fell again last month. Amanda Bryden, Head of Mortgages at Halifax, commented: "Property price trends continue to reflect the uncertainty linked to developments in the Middle East." What does this mean? For buyers, the latest figures underline just how stretched affordability has become. For sellers and estate agents, they reinforce the close relationship between property prices, buyer confidence and the cost of borrowing. While interest rates and market conditions will continue to evolve, understanding your financial position before making major decisions has never been more important. Final thoughts The housing market continues to adjust to a period of higher borrowing costs and greater economic uncertainty. Whether you're buying your first home, moving property or simply reviewing your finances, taking time to understand what you can comfortably afford is just as important as finding the right property. If you'd like to discuss your finances or how changing economic conditions could affect your plans, I'm always happy to have a straightforward conversation. Talk to us about your finances.
Government moves towards public ownership British Steel is set to return to public ownership after Prime Minister Sir Keir Starmer announced plans for new legislation that would give the Government the power to take full control of the company. The proposed move will be subject to a public interest test, considering factors such as national security, critical infrastructure and wider economic support. The announcement follows the Government's intervention at British Steel's Scunthorpe steelworks in April last year. At the time, ministers stepped in and took control of the site from its Chinese owner, Jingye, to prevent the possible closure of its blast furnaces. Why is the Government stepping in? Sir Keir Starmer said the Government had held discussions with Jingye in an attempt to find a commercial solution, but no sale could be agreed. As a result, ministers concluded that bringing British Steel back into public ownership was now "in the public interest". The decision reflects the strategic importance of steel production to the UK economy, particularly at a time when supply chains, manufacturing resilience and national security remain high on the political agenda. A welcome boost for the industry The announcement has been broadly welcomed by the steel industry. Gareth Stace, Director-General of UK Steel, said the move provides "vital certainty" for British Steel's 2,700 employees , as well as reassurance for customers who rely on domestic steel production. He also highlighted the wider importance of maintaining a UK steel industry, describing it as essential for economic growth, national security and long-term resilience. However, he also cautioned that public ownership should not be viewed as the end of the process. Instead, he said it should mark the beginning of a clear long-term strategy, backed by sustained investment to secure the company's future. Why Scunthorpe matters The future of the Scunthorpe steelworks has attracted particular attention because its blast furnaces play a vital role in the UK's ability to produce virgin steel. If those furnaces were to be switched off, restarting them would be both technically difficult and extremely expensive. That makes decisions around the site important not only for local employment, but also for the UK's long-term industrial capability. The cost of intervention Government involvement has already come at a significant cost. The National Audit Office reported in March that Government supervision of British Steel had already cost around £377 million . If expenditure continues at a similar rate, the total could exceed £1.5 billion by 2028 . At this stage, the overall cost of full nationalisation has not been confirmed. An independent valuation is expected to determine whether compensation should be paid to Jingye as part of the process. Final thoughts The proposed return of British Steel to public ownership represents a significant development for one of the UK's most strategically important industries. While the move has been welcomed by many within the sector, attention will now turn to the long-term plan for the business and the level of investment needed to secure its future. For businesses, it's another reminder that Government policy, global markets and economic resilience remain closely linked, with decisions in one area often having wider implications across the economy. If you'd like to discuss how wider economic developments could affect your business, I'm always happy to have a straightforward conversation. Talk to us about your business.
Director's Loans: How to Avoid Unexpected Tax Bills As a business owner, there will probably come a time when you need to take money out of your limited company outside of your normal salary or dividends. It might be to cover a personal expense, help with a house purchase, or simply smooth your cash flow. There's nothing unusual about that. In fact, director's loans are common in owner-managed businesses. What many people don't realise, though, is that director's loan accounts come with some fairly strict tax rules. If they're not managed properly, they can trigger unexpected Corporation Tax charges, benefit-in-kind issues and additional reporting requirements. With the Section 455 tax rate increasing for new loans made from 6 April 2026, it's more important than ever to keep an eye on your director's loan account. Here's what you need to know. What is a Director's Loan Account? A director's loan account (DLA) simply records money moving between you and your company that isn't: Salary Dividends Reimbursed business expenses Genuine business purchases If you've put your own money into the business, your company owes you, creating a credit balance. If you've taken money from the company for personal use, and it isn't salary or dividends, you owe the company, creating an overdrawn (debit) balance. For most small limited companies, this matters because they're classed as "close companies" for tax purposes. Broadly speaking, that's a company controlled by five or fewer shareholders, which covers the vast majority of owner-managed businesses. According to government estimates, there were around 2.1 million actively trading companies in the UK at the start of 2025, so these rules affect a huge number of business owners. When Does Section 455 Tax Apply? If your director's loan account is overdrawn at the end of your company's accounting period and you haven't repaid it within nine months and one day after the year-end, your company may have to pay a Section 455 tax charge. For loans made on or after 6 April 2026 , the charge is 35.75% . Loans made between 6 April 2022 and 5 April 2026 generally remain subject to the previous 33.75% rate. For example: If your company has a 31 March 2027 year-end and you borrow £40,000 in May 2026, but the balance is still outstanding on 1 January 2028 , your company could face a Section 455 tax charge of £14,300 . The important point is that this tax is paid by the company, not you personally. It's reported through the Corporation Tax return using the CT600A supplementary pages . The good news is that Section 455 isn't a permanent tax. Once the loan is repaid, written off or released, the company can usually reclaim it. However, the money may remain with HMRC for quite some time, so it can still create a significant cash flow issue. It's also worth remembering that: Several smaller withdrawals throughout the year can create exactly the same problem as one large loan. The rules generally apply to loans made to shareholders (participators) and people connected to them. Separate personal tax charges can also arise if the loan is interest-free or later written off. Are There Any Exemptions? Yes, although they don't apply to most owner-managed businesses. The main exemptions include: Loans of £15,000 or less to a full-time employee or director who owns no more than 5% of the company. Normal commercial trade credit. Companies whose normal business is lending money. For most small companies, it's safest to assume that an overdrawn director's loan account could trigger Section 455 unless it's cleared correctly and on time. Don't Forget the £10,000 Rule Section 455 isn't the only tax issue to be aware of. If at any point during the tax year you owe the company more than £10,000 , and you aren't paying interest (or you're paying less than HMRC's official rate), you could have a taxable benefit-in-kind. HMRC's official interest rate is currently 3.75% (from 6 April 2025 and reviewed quarterly). If this applies: You'll pay income tax on the interest you've effectively saved. The company must report the benefit on a P11D . The company also pays Class 1A National Insurance at 15% for 2026/27. This catches more people than you'd think because it's completely separate from the Section 455 rules. You could repay the loan quickly enough to avoid Section 455 altogether, but still have a taxable benefit because your balance exceeded £10,000 during the tax year. The simplest way to avoid this is to keep the balance below £10,000 where possible. If that's not realistic, the company should charge interest at HMRC's official rate and make sure it's actually paid. I'd also recommend having a proper written loan agreement that sets out the amount borrowed, interest rate and repayment terms. Why Repaying and Borrowing Again Doesn't Work Every year, HMRC sees directors repay loans just before the deadline before taking the money back out shortly afterwards. They've introduced anti-avoidance rules specifically to stop this. The first is the 30-day rule , which can apply where repayments of £5,000 or more are followed by new borrowing of £5,000 or more within 30 days. The second is known as the arrangements rule . This can apply where at least £15,000 is outstanding before repayment and there was already an intention to borrow at least £5,000 again afterwards. In both cases, HMRC looks at the substance of what's happened rather than simply the dates on your bank statement. In short, if you're only repaying the loan so you can immediately borrow it again, don't expect it to solve the problem. What If the Loan Is Written Off? Sometimes directors simply can't repay the money. While the company can write off a director's loan, it isn't usually the easy solution people hope for. Where the director is also a shareholder, the amount written off is normally treated as a dividend for income tax purposes. For 2026/27 , dividend tax rates are: 10.75% for basic rate taxpayers 35.75% for higher rate taxpayers 39.35% for additional rate taxpayers The dividend allowance remains just £500 , so most of the written-off amount is likely to be taxable. There may also be National Insurance and employment tax implications depending on the circumstances. The company can generally reclaim any Section 455 tax once the loan has been released or written off, but the personal tax bill often makes this an expensive option. Reclaiming Section 455 Tax Although Section 455 can usually be reclaimed, the process isn't immediate. HMRC only allows relief nine months and one day after the end of the accounting period in which the loan was repaid, released or written off . To make the claim, you'll need details including: When the original loan was made The amount borrowed When it was repaid, released or written off The value of each repayment If only part of the loan has been repaid, partial relief may still be available. Why Good Records Matter More Than Ever The increase to the new 35.75% Section 455 rate means many companies could now have older loans at 33.75% alongside newer loans taxed at the higher rate. When repayments are made, it's sensible to record exactly which loan they're intended to clear. Without clear records, HMRC may apply default rules that don't produce the most tax-efficient outcome. It doesn't need to be complicated. Even a simple email confirming that a repayment relates to a specific loan can make life much easier if questions arise later. Practical Tips to Stay Out of Trouble Director's loan accounts don't need to become a headache, provided you stay on top of them. I'd recommend: Reviewing your director's loan account every month rather than waiting until year-end. Planning dividends properly and only paying them when sufficient retained profits exist. Keeping an eye on the £10,000 benefit-in-kind threshold. Avoiding artificial repayments followed by immediate re-borrowing. Having written loan agreements for larger balances. Clearly recording which loans repayments relate to. Reviewing the position well before your company year-end while you still have planning options available. Final Thoughts Director's loan accounts can be a useful way of managing cash flow and giving yourself flexibility as a business owner. The problems only tend to arise when they're left unchecked. With the Section 455 rate now increasing to 35.75% for new loans from 6 April 2026 , it's well worth reviewing your position regularly rather than waiting until the accounts are prepared. If you're unsure whether your director's loan account is causing a tax issue, or you're thinking about taking money from your company, I'd always recommend getting advice early. A quick conversation now could save you a much larger tax bill later. If you'd like us to review your director's loan account or answer any questions, please get in touch. We'd be happy to help.
Consumer confidence falls as concerns over inflation return A new survey suggests that many British households are preparing for renewed financial pressure as conflict in the Middle East weighs on economic confidence. Consumer confidence in the UK fell at its fastest quarterly rate since June 2022, when inflation surged following Russia's invasion of Ukraine and the resulting rise in global commodity prices. The survey, which measures factors such as spending intentions and how financially secure people feel, recorded a score of -13 in April . That represents a significant decline from -1 in January and marks the weakest reading since autumn 2023. While confidence has weakened across all age groups, the figures suggest that no part of the population is entirely immune to growing concerns about the economy. Financial confidence falls across generations Younger consumers remain more optimistic than older age groups overall, but confidence among under-35s has also deteriorated. The proportion of younger people who described themselves as financially healthy fell by 20% , while the share reporting that they were struggling or finding it difficult to manage bills and finances increased by 9% . These figures highlight the growing pressure many households continue to face, despite inflation having fallen significantly from its peak. Cost-of-living concerns remain widespread The survey found that concerns about household finances remain firmly linked to the cost of living. Almost 90% of the 2,068 consumers surveyed said they were concerned about living costs, while nearly 80% said they planned to reduce spending over the next three months. When consumers begin cutting discretionary spending, the effects can often be felt across a wide range of sectors, particularly those reliant on consumer confidence and household spending. Rising fuel costs are changing behaviour Higher fuel prices are already influencing everyday decisions. The proportion of consumers planning to drive less in order to save money has doubled since January, increasing from 12% to 24% . While fuel costs are only one part of household budgets, they tend to have a visible impact because they affect commuting, travel and day-to-day living costs almost immediately. Inflation pressures remain The Bank of England has indicated that higher UK inflation is likely to be "unavoidable" as a result of the conflict in the Middle East. Rising fuel, food and energy costs are expected to add further pressure to household budgets in the months ahead. Recent figures from the Office for National Statistics (ONS) showed that CPI inflation rose to 3.3% in March , up from 3% in February and remaining above the Bank of England's 2% target . While inflation is significantly lower than the peaks seen in recent years, any upward movement is likely to be closely watched by policymakers, businesses and consumers alike. What is happening in the jobs market? The employment picture remains mixed. Job vacancies fell again in April, marking the 30th consecutive monthly decline . However, there are signs that employers are responding to uncertainty by increasing their use of temporary workers rather than committing to permanent recruitment. Temporary billings rose at their strongest pace in two-and-a-half years , suggesting that some businesses remain cautious about long-term hiring decisions while economic conditions remain uncertain. Final thoughts The latest survey paints a picture of households becoming more cautious as concerns about inflation, energy costs and the wider economy return to the forefront. While confidence figures can move quickly, they often provide a useful indication of how consumers are feeling and how they may behave in the months ahead. For individuals and businesses alike, periods of uncertainty reinforce the importance of understanding cashflow, reviewing spending and planning ahead wherever possible. Talk to us about your finances.
Rising costs and weaker demand continue to challenge the industry UK construction firms are facing some of the sharpest cost increases seen in almost 30 years, as the conflict involving Iran pushes up fuel, energy and raw material prices. A closely watched survey of UK construction businesses found that input cost inflation rose significantly in April, reaching its highest level since June 2022, when commodity prices surged following Russia's invasion of Ukraine. In fact, April's increase in purchasing costs was among the steepest recorded since the survey began in 1997. At the same time, activity across the sector continues to weaken. The Construction Purchasing Managers' Index (PMI), one of the key indicators of activity in the industry, fell to 39.7 in April , down from 45.6 in March . Any reading below 50 indicates contraction, suggesting that many firms are seeing workloads and activity levels decline. A difficult backdrop for the industry These pressures come at a challenging time for a sector that contributes around 7% of UK GDP and employs more than two million people . Construction businesses have already been dealing with a combination of: Weaker demand Ongoing skills shortages Higher operating costs Increased financing costs The latest rise in input prices only adds to those challenges. Around two-thirds of firms surveyed reported higher costs during April. Many businesses pointed to suppliers passing on increased fuel and transport costs linked to the conflict in the Middle East, disruption in the Strait of Hormuz, and rising prices for imported materials. Supply chain issues continue Alongside higher costs, supply chains are once again showing signs of strain. Vendor delivery times lengthened at the fastest pace since December 2022 , with firms reporting delays to international shipping and difficulties sourcing materials from parts of the Gulf region. For many construction businesses, delays can be almost as damaging as price increases. Longer lead times make project planning more difficult, affect cashflow and can create challenges when managing customer expectations. New work remains subdued Perhaps the bigger concern is that new work is not always replacing completed projects quickly enough. The survey found that sales decisions are taking longer, reflecting ongoing caution among customers and investors. In some cases, businesses are responding by reducing recruitment activity or choosing not to replace employees who leave voluntarily. While that approach may help control costs in the short term, it also highlights the level of uncertainty many firms are currently experiencing. Final thoughts Construction remains an important part of the UK economy, but the sector is facing pressure from several directions at once. Rising input costs, supply chain disruption, slower decision-making and weaker demand are creating a challenging environment for many businesses. While external events may be outside a company's control, understanding margins, monitoring cashflow and planning ahead become even more important during periods like this. If you're running a construction business and would like to discuss cashflow, profitability or managing rising costs, I'm always happy to have a conversation. Talk to us about your business.
Working abroad: Getting your UK tax residence right How to manage your UK tax position when living or working overseas Spending time abroad for work has become much more common. Whether you're relocating for a new role, taking an overseas posting, working remotely from another country or returning to the UK after several years away, it's important to understand how UK tax rules apply. One of the biggest surprises for many people is that leaving the UK does not automatically make you non-resident for tax purposes. Equally, becoming non-resident does not necessarily remove you from the UK tax system altogether. Understanding your tax position before you leave, while you're abroad and before you return can help avoid unexpected tax bills and unnecessary complications later. Why tax residence matters Your UK tax residence status determines how much of your income and gains fall within the UK tax system. Generally speaking: UK residents are taxed on their worldwide income and gains, subject to available reliefs and double tax treaties. Non-UK residents are usually taxed only on UK-source income, certain UK gains and a limited range of other UK-related income. Getting your residence status wrong can be expensive. If HMRC later concludes that you remained UK resident when you believed you were non-resident, overseas salary, foreign investment income and offshore gains could all become subject to UK tax, together with interest and potential penalties. That's why residence planning is something to consider before you move rather than after the tax return deadline arrives. Understanding the Statutory Residence Test Since 2013, UK tax residence has been determined by the Statutory Residence Test (SRT). The test follows a specific order: Automatic overseas tests Automatic UK tests Sufficient ties test If you meet one of the automatic overseas tests, you are generally non-UK resident for the tax year. If not, the automatic UK tests are considered. If neither set of tests gives a clear answer, the sufficient ties test applies. At the heart of the SRT is day counting. In most cases, a day counts as a UK day if you are present in the UK at midnight. There are limited exceptions, including certain transit days and exceptional circumstances. There is also a deeming rule that can catch people making repeated short visits. If you were UK resident in one of the previous three tax years, have at least three UK ties and spend more than 30 days in the UK without being here at midnight, some of those days can still count towards your UK day total. For anyone close to the limits, accurate records are essential. The automatic overseas tests The clearest route to non-residence is meeting one of the automatic overseas tests. You will generally be non-UK resident if: You were UK resident in one or more of the previous three tax years and spend fewer than 16 days in the UK during the current tax year. You were not UK resident in any of the previous three tax years and spend fewer than 46 days in the UK. You work full-time overseas, have no significant break from overseas work, spend fewer than 91 days in the UK and work more than three hours in the UK on fewer than 31 days. For many people moving abroad for work, the full-time overseas work test is the most relevant. However, it is also one of the easiest tests to fail accidentally through too many UK workdays, extended return visits or gaps between overseas contracts. For SRT purposes, full-time overseas work broadly means averaging at least 35 hours per week overseas under HMRC's detailed calculation rules. A significant break is usually a period of 31 consecutive days or more without overseas work, although certain absences such as annual leave and sickness can be ignored. The automatic UK tests If none of the overseas tests apply, the UK tests are considered. You will generally be UK resident if: You spend 183 days or more in the UK during the tax year. You have a UK home available for at least 91 continuous days, use it for at least 30 days, and have little or no qualifying overseas home. You work full-time in the UK over a 365-day period and more than 75% of your workdays fall in the UK. The UK home test often catches people out. Many individuals assume they have left the UK because they live and work overseas, but continue to retain and regularly use a UK property. The position needs careful review because retaining access to a UK home can have a significant impact on residence status. The sufficient ties test If neither automatic test provides an answer, the sufficient ties test applies. The more ties you have to the UK, the fewer days you can spend here before becoming UK resident. The five main ties are: Family tie Accommodation tie Work tie 90-day tie Country tie The country tie only applies to people leaving the UK and is met when the UK is the country where you spend the greatest number of days. This explains why two people can spend exactly the same number of days in the UK but reach different residence outcomes. Split year treatment Normally a tax year is treated as either fully resident or fully non-resident. However, split year treatment may divide the year into a UK part and an overseas part. There are eight separate circumstances where split year treatment can apply, including: Starting full-time work overseas Ceasing to have a UK home Accompanying a partner who starts full-time work overseas Starting full-time work in the UK Establishing a UK home For those leaving the UK for employment abroad, starting full-time overseas work is often the most common route. Split year treatment is not automatic and must be claimed correctly through the SA109 supplementary pages of your Self Assessment return. What remains taxable if you're non-resident? Becoming non-resident does not remove all UK tax obligations. UK tax may still apply to: Rental profits from UK property Employment income relating to duties carried out in the UK Certain UK pensions Gains on UK property and land Certain UK-source investment income Non-residents selling UK property will usually need to report the disposal to HMRC within 60 days of completion, even where no tax is payable. Landlords may also need to register under the Non-Resident Landlord Scheme, under which tax can be deducted from rental income unless HMRC approves gross payment. Double tax treaties can help prevent the same income being taxed twice, although the exact position depends on the treaty involved. National Insurance matters too Income tax residence and National Insurance follow different rules. Depending on your circumstances, you may continue paying UK National Insurance while working abroad, particularly where: You are temporarily posted overseas by a UK employer. A social security agreement applies. An A1 certificate or certificate of coverage is available. There has also been an important change to voluntary National Insurance. From 6 April 2026, people can no longer pay voluntary Class 2 National Insurance contributions while abroad. Class 3 contributions may still be available, but new applications generally require either: 10 continuous years of UK residence, or 10 qualifying years on your National Insurance record. Anyone moving overseas should review their State Pension position before they leave. The four-year FIG regime The rules for people arriving in or returning to the UK changed significantly from 6 April 2025. The remittance basis has been abolished and replaced by a residence-based system. Under the new Foreign Income and Gains (FIG) regime, qualifying individuals may claim relief on eligible foreign income and gains during their first four years of UK residence. To qualify, you generally need to be returning after at least 10 consecutive tax years of non-UK residence. There are two important points to remember: Claiming FIG relief means losing your UK Personal Allowance and Capital Gains Tax annual exempt amount. The four-year period cannot be extended if relief is not claimed in a particular year. Former remittance basis users may also be able to use the Temporary Repatriation Facility, which allows certain pre-6 April 2025 foreign income and gains to be brought to the UK at reduced tax rates. The published rates are: 12% for 2025/26 and 2026/27 15% for 2027/28 The facility closes after 5 April 2028. Beware temporary non-residence rules One of the most common traps is assuming that a short move abroad allows income or gains to be realised tax-free. The temporary non-residence rules can bring certain income and gains back into the UK tax net when you return. They can apply to: Capital gains Dividends from close companies Certain pension payments Certain company winding-up distributions A notable change announced in the November 2025 Budget removed the post-departure trade profits carve-out for dividends and distributions from close companies. For individuals returning to the UK on or after 6 April 2026, all such dividends received while temporarily non-resident can fall within the rules regardless of when the profits arose. In most cases, you need to be non-resident for at least five complete tax years for the temporary non-residence rules not to apply. Keep good records If HMRC ever challenges your residence position, the burden of proof generally rests with you. Useful records include: Travel records and boarding passes Day-by-day UK presence logs Accommodation records Employment contracts Work calendars Evidence relating to UK homes Family records where relevant For most people, a simple spreadsheet recording travel dates and UK workdays is sufficient. Planning before you leave Before moving abroad, consider: How many UK days you can spend here Whether you satisfy the full-time overseas work test Whether a UK property creates issues Whether split year treatment is available How UK work duties will be taxed Whether rental income requires NRL registration National Insurance implications Double tax treaty protection It's also important to remember that overseas remote working can create tax, payroll, employment law and corporate tax issues for your employer as well. Planning before you return Before returning to the UK, review: Whether the FIG regime is available Whether temporary non-residence rules apply The timing of income and gains Whether foreign assets should be sold before returning Whether the Temporary Repatriation Facility may help The impact of your chosen return date In some cases, returning on 5 April rather than 6 April can produce a very different tax outcome. Final thoughts Working abroad can be tax-efficient with the right planning. Without it, it can create unexpected tax bills, reporting obligations and complications both in the UK and overseas. The most important decisions are often made before the move takes place. Understanding your residence position, managing your UK ties and planning your return can make a significant difference to the eventual tax outcome. If you're planning to move overseas, already working abroad, or considering a return to the UK, it's worth reviewing your position early. A little planning now can save a lot of time, tax and stress later. If you'd like advice tailored to your circumstances, please get in touch.
Why markets are paying close attention to political and economic uncertainty Government borrowing costs have risen sharply in recent weeks as investors react to growing uncertainty around the future of Prime Minister Keir Starmer and wider economic pressures. The effective interest rate on 10-year Government borrowing briefly reached 5.13% , close to levels last seen during the 2008 financial crisis. Longer-term borrowing also came under pressure, with the 30-year gilt yield rising to 5.81% , its highest level since 1998. While financial markets move constantly, these figures highlight how quickly investor sentiment can change when uncertainty increases. What's driving the increase? Markets were already unsettled by the conflict involving Iran, which pushed oil prices above $100 per barrel and increased concerns about inflation. Higher energy prices often feed through into the wider economy, raising costs for businesses and consumers. If inflation rises, investors may begin to expect interest rates to remain higher for longer. That matters because higher interest rates typically increase borrowing costs throughout the economy. Why the UK has been affected more than some other countries Although many countries have faced similar global pressures, the UK's borrowing costs rose more sharply than those seen in economies such as France and Germany. Analysts suggested that some investors were also concerned about the possibility of changes within the Labour leadership and what that could mean for future Government spending. There are concerns in some parts of the market that a change in direction could result in higher public spending and increased Government borrowing. Prime Minister Keir Starmer and Chancellor Rachel Reeves have repeatedly described their fiscal rules as "iron-clad" and have committed to maintaining strict borrowing controls. However, some Labour MPs have questioned whether the current fiscal framework is suitable for delivering long-term economic renewal. Understanding gilts Government borrowing is largely carried out through bonds known as gilts . Investors effectively lend money to the Government in exchange for interest payments over a fixed period. As with any investment, the perceived level of risk influences the return investors demand. If confidence falls or uncertainty rises, investors generally require higher returns before committing their money. That is why borrowing costs can rise even when no immediate policy changes have been announced. Wider market reaction The impact was felt beyond the gilt market. Bank shares and sterling also reacted as investors assessed the possibility of future tax changes and shifts in economic policy under a different political landscape. However, short-term market movements can be volatile and often reverse quickly. The more significant point is that investors remain highly sensitive to uncertainty around fiscal policy, Government spending and economic direction. What does this mean for businesses and households? For most businesses and households, rising gilt yields are not something that affects day-to-day decisions directly. However, they can influence the wider economy through: Interest rate expectations Mortgage pricing Business borrowing costs Investment confidence Government spending decisions While one day's market movement rarely tells the whole story, periods of uncertainty often remind us how closely financial markets watch Government policy and economic stability. Final thoughts The recent rise in UK borrowing costs reflects a combination of global pressures and domestic political uncertainty. Whether these increases prove temporary or more persistent remains to be seen, but the reaction highlights how quickly markets can respond when confidence is tested. For businesses, the key takeaway is to continue focusing on the fundamentals: cashflow, profitability and planning ahead for changing economic conditions. If you'd like to discuss how wider economic developments may affect your business or personal finances, I'm always happy to have a conversation.
Review systems, suppliers and processes before the deadline E-invoicing is moving from being a back-office efficiency project to something UK businesses need to start planning for. The Government has confirmed that all VAT invoices will need to be issued as e-invoices from April 2029 . In practice, this mainly affects business-to-business and business-to-government VAT invoices rather than standard business-to-consumer sales. While the detailed UK standards and roadmap are still being developed, businesses that start preparing now are likely to find the transition much easier. For most SMEs, the answer is not to rush into replacing systems overnight. Instead, the focus should be on getting the fundamentals right: invoice data, VAT treatment, software capability, customer and supplier records, approval processes and payment controls. A business that gets those foundations in place now will be in a much stronger position when the final requirements arrive. Understanding what e-invoicing actually means One of the biggest misconceptions is that e-invoicing simply means sending invoices by email. It doesn't. The Government defines e-invoicing as the digital exchange of invoice information directly between a supplier’s and customer’s financial systems. The invoice is issued, transmitted and received in a structured format that allows it to be processed automatically. If your business currently creates an invoice, saves it as a PDF and emails it to a customer who then manually enters the information into their own system, that's still a largely manual process. A structured e-invoice is different because the information moves automatically between systems without rekeying. That distinction matters because it reduces: Manual errors Processing delays Missing information Duplicate data entry Invoice disputes Many SMEs are still not ready HMRC research published in March 2026 found that: 59% of VAT-registered SMEs said they were familiar with e-invoicing Only 29% said they actually used it PDF and email invoicing remained the most common approach Paper invoicing was still used by some businesses The gap between familiarity and actual use highlights why preparation matters. Why businesses should start thinking about this now Although 2029 may seem a long way off, e-invoicing affects much more than tax compliance. It touches: Sales invoicing Purchase ledger processes Customer approvals Supplier relationships Credit control Cashflow management Government consultations have consistently highlighted benefits such as: Fewer errors Faster processing Improved compliance Greater automation Better cashflow visibility The cashflow aspect is particularly interesting. Government figures published in March 2026 estimated that UK businesses are owed around £26 billion in late payments at any given time , with affected firms owed an average of £17,000 each . More than 1.5 million businesses are impacted annually, spending an average of 86 hours per year chasing overdue payments. E-invoicing won't eliminate late payment entirely, but it can remove many of the avoidable issues that delay payment, such as: Missing purchase order numbers Incorrect VAT treatment Duplicate invoices Approval bottlenecks Data entry errors There is also a fraud angle The Government's Fraud Strategy 2026–2029 highlights the growing problem of criminals intercepting invoices and impersonating legitimate suppliers. One of the aims of mandatory e-invoicing is to reduce these risks by moving invoice exchanges into secure digital systems rather than relying heavily on email. That means e-invoicing is not just about compliance. It's also about improving security. The current position for 2026/27 For the 2026/27 tax year: The standard VAT rate remains 20% The VAT registration threshold remains £90,000 The VAT deregistration threshold remains £88,000 Because the proposed mandate relates to VAT invoices, businesses that are not VAT registered will not be required to adopt e-invoicing solely because of the new rules. However, some smaller businesses may still find themselves adopting it if larger customers or suppliers begin requiring structured invoice formats. The wider direction of travel is clear. Alongside Making Tax Digital, HMRC continues to move towards greater automation and digital record-keeping. Practical steps SMEs can take now Review your invoicing process Start by understanding how invoices currently move through your business. Ask yourself: Where is invoice data created? Who checks VAT treatment? How often are invoices delayed due to missing information? Do customers reject invoices because of formatting issues? How much manual rekeying still takes place? Often the biggest inefficiencies are not in the software itself, but in the processes around it. Separate document format from data format Many businesses assume they're already prepared because invoices are generated digitally. However, creating a PDF is not the same as structured e-invoicing. When speaking to software providers, focus on how invoice data moves between systems, not simply how the invoice looks on screen. Clean up customer and supplier records Structured invoicing relies on accurate data. Review: Legal entity names VAT numbers Billing addresses Purchase order requirements Contact details Payment terms The cleaner the data, the smoother the transition will be. Review VAT treatment Now is a good time to check whether invoices consistently apply: The correct VAT rates Exemption rules Reverse charge requirements Appropriate invoice wording Any weaknesses in VAT coding are likely to become more visible in automated systems. Speak to your software provider Most accounting software providers are already developing their e-invoicing capabilities. Ask practical questions such as: Can the software send and receive structured e-invoices? What formats does it support? How will future UK changes be handled? Can invoice fields be validated automatically? How are rejected invoices managed? Understanding the roadmap now can avoid surprises later. Focus on key customers and suppliers first Not every relationship needs attention immediately. Start with: High-value customers High-volume customers Suppliers where invoice issues regularly occur A phased approach is often more manageable than attempting a wholesale change. Strengthen approval and fraud controls Even with structured invoicing, businesses still need processes for: Invoice disputes Credit notes Duplicate invoices Supplier bank detail changes Validation failures Good controls remain essential. Final thoughts The best way to view e-invoicing is not as a single compliance deadline in 2029, but as part of a broader shift towards cleaner data, better systems and less manual administration. For SMEs, preparation doesn't mean panic. It means taking practical steps now: Reviewing invoicing processes Cleaning up customer and supplier data Checking software capability Testing VAT treatment Strengthening controls Businesses that start that work early are likely to find the eventual transition far smoother, less disruptive and less expensive. If you'd like help reviewing your invoicing processes, bookkeeping systems or software setup ahead of the changes, get in touch. You may also be interested in: E-invoicing rollout leaves many SMEs unprepared
What businesses should know ahead of the 2029 changes Many small businesses still appear unclear about the Government’s planned move towards mandatory electronic invoicing, with most reporting they have not seen guidance from HMRC ahead of the rollout. At the Autumn Budget, Chancellor Rachel Reeves confirmed that from April 2029 , all VAT-registered businesses will be required to issue invoices electronically as part of wider plans to modernise the UK tax system. Despite the scale of the change, the announcement attracted relatively little attention at the time. There have also been concerns around the lack of a phased introduction for smaller businesses that may still rely on manual processes or older systems. What the research found Research commissioned by HMRC and carried out by IFF Research surveyed 800 SMEs across sectors including manufacturing, transport and business services. The findings suggest there is still a significant knowledge gap around e-invoicing: 25% of respondents said they were not at all familiar with the term “e-invoicing” 69% said they had never used it 91% reported not seeing any HMRC guidance on the upcoming changes That said, there is some nuance behind the figures. The Association of Taxation Technicians pointed out that several businesses initially claimed not to use e-invoicing, but later described processes that actually met the definition. Those responses were later reclassified. Some businesses are already using it without realising Encouragingly, the research also showed: 59% of SMEs were at least somewhat familiar with e-invoicing 29% reported having used it previously Among those already using e-invoicing software: Sage was the most commonly used platform at 46% Xero followed at 17% QuickBooks accounted for 9% Only a small minority (around 5% ) reported using no accounting software at all, although this was more common in manufacturing and construction. Why this matters For many businesses, the move to e-invoicing will probably feel less dramatic than it sounds, particularly if they already use cloud accounting software. However, for others still relying heavily on spreadsheets, PDFs or manual invoicing processes, the change may require adjustments to systems and workflows over the next few years. The wider direction of travel is clear. HMRC continues moving towards greater digital reporting and automation through initiatives such as Making Tax Digital, and e-invoicing forms part of that broader shift. Final thoughts Although April 2029 may still sound a long way off, these types of changes are usually easier to deal with gradually rather than leaving them until the last minute. For some businesses, it may simply mean reviewing existing systems and checking they are compatible. For others, it could be the point where moving to proper accounting software becomes necessary. Either way, understanding how your current processes work now will make future changes far easier to manage. If you want to review whether your bookkeeping and invoicing systems are working efficiently for your business, please get in touch. This may be of interest to you: Spotlight on: Making Tax Digital for Income Tax.
The increase in HMRC’s approved mileage rate for cars and vans from 45p to 55p per mile has certainly generated some headlines today. On the surface, it sounds simple: “Drivers get 10p more per mile tax free.” The reality is a bit more nuanced. It Doesn’t Apply to Everyone Firstly, this only applies to cars and vans. Motorcycle rates remain at 24p (close to my heart of course), and bicycle rates stay at 20p. Secondly, the HMRC mileage rates are approved allowances, not mandatory reimbursement rates. Businesses are not legally required to pay 55p per mile unless contracts or internal policies say otherwise. Employees May Still Be Able to Claim Relief If an employer continues paying below the approved rate, employees may instead be able to claim tax relief on the difference from HMRC. The Real Cost for Businesses There’s also a wider business impact that many of the headlines ignore. If employers do choose to increase mileage reimbursements, the majority of the additional cost sits with the business itself. Corporation tax relief softens the blow slightly, but only by around 20–25% depending on the business. In other words, roughly 75–80% of the increase is still a real additional cost to the employer. For businesses with travelling staff, care workers, sales teams, engineers or multi-site employees, this could become a significant additional expense at a time when many are already under pressure. The Practical Work Starts Now As always with tax announcements, the headline is the easy part. The implementation, payroll updates, policy reviews and practical implications are where the real work starts. And for many businesses, that’s where the real cost begins too.
More businesses to receive help with rising energy costs The Government has confirmed it will expand a support scheme aimed at helping energy-intensive manufacturers manage rising electricity costs. Around 10,000 UK manufacturers could now benefit from reduced electricity bills under the expanded British Industrial Competitiveness Scheme (BICS) . The original proposal, announced in 2025, covered around 7,000 businesses , meaning an additional 3,000 companies have now been brought into scope. The scheme applies to energy-intensive sectors including: Steel Automotive Pharmaceuticals Why the scheme is being expanded The move comes after continued pressure from high energy prices. Oil and gas costs rose sharply during recent geopolitical tensions. Although prices have eased somewhat since then, UK manufacturers are still facing significantly higher energy costs than competitors in parts of Europe and the United States. For many businesses, energy remains one of the biggest operational pressures, particularly in sectors where electricity usage forms a large part of overall costs. What support businesses could receive From April 2027 , eligible companies will be exempt from certain electricity charges linked to net zero policies. The Government estimates this could reduce costs by around £35 to £40 per megawatt hour . There will also be a one-off payment in 2027 to compensate businesses for support they would otherwise have received from April 2026 . The overall scheme is expected to cost around £600 million . According to the Government, funding will come from wider energy system reforms and public spending, with no additional impact on household energy bills. Businesses will be able to check whether they qualify using their Standard Industrial Classification (SIC) code . Reaction from businesses Business groups have generally welcomed the announcement, although some believe the support still does not go far enough. Critics have pointed out that sectors such as: Hospitality Retail Agriculture remain outside the scheme, despite continuing to face significant cost pressures of their own. Industry bodies continue to warn that energy costs remain a major issue across the wider economy. Recent figures suggest around four in ten UK businesses are still struggling to manage energy bills. Final thoughts For manufacturers affected by high electricity costs, the expansion of the scheme may provide some longer-term relief and greater certainty around operating costs. However, the wider challenge around energy pricing in the UK has not disappeared, and many businesses outside the scheme will still be dealing with significant pressure on margins and cashflow. As always, understanding how rising costs affect profitability and planning ahead remains important, particularly in sectors where overheads can change quickly. If you’d like to talk through rising business costs or how they are affecting your numbers, I’m always happy to have a conversation .
SPOTLIGHT ON: Giving to charity - Tax reliefs you can use Simple ways to use the reliefs available on qualifying gifts Giving to charity is usually driven by personal values rather than tax planning, but the tax treatment still matters. Used properly, the available reliefs can help a donation go further, reduce your tax bill, or both. HMRC’s latest charity tax relief statistics show that charitable tax reliefs were worth around £6.7 billion in the year to April 2025, including £1.7 billion of Gift Aid paid to charities. For individuals, the main UK reliefs sit in four areas: Gift Aid Payroll Giving Gifts of shares or property Charitable gifts left in a will Each works differently. Sometimes the charity receives the tax benefit. In other cases, you claim relief yourself. The right approach depends on what you are giving, how often you give, and your wider tax position in the 2026/27 tax year . Start with Gift Aid For most people, Gift Aid is the first thing to review. If you make a qualifying donation under Gift Aid, the charity can claim an extra 25p for every £1 donated , at no additional cost to you. To use Gift Aid, you need to complete a declaration with the charity. That declaration can cover: Current donations Future donations Donations made in the previous four years Gift Aid is straightforward, but it is not automatic. You should only complete a Gift Aid declaration if you have paid enough UK Income Tax or Capital Gains Tax to cover the amount the charity will reclaim. HMRC states that your Gift Aid donations in a tax year must not exceed four times the amount of qualifying tax you have paid. If a charity reclaims more tax than you have actually paid, HMRC can ask you to pay the difference. This catches people out more often than many realise, particularly: Retirees Students Lower earners People whose dividend or savings income falls within allowances and generates little actual tax liability Before ticking the Gift Aid box, it is worth checking your position properly. What does not qualify for Gift Aid? Gift Aid is not available: Where the payment is really for goods or services Where the donor receives benefits above permitted limits For Payroll Giving donations For gifts of shares (which have separate relief rules) Higher-rate taxpayers may be missing extra relief One of the most commonly overlooked areas is the additional tax relief available to higher and additional-rate taxpayers. If you pay tax above the basic rate, you may be able to reclaim the difference between your rate of tax and the basic-rate relief already claimed by the charity. HMRC says this can be claimed either: Through Self Assessment Or by asking HMRC to adjust your tax code For example: A £100 donation under Gift Aid becomes £125 gross to the charity A 40% taxpayer can then reclaim £25 A 45% taxpayer can reclaim £31.25 A lot of people tick the Gift Aid box and assume the process ends there. In reality, many higher-rate taxpayers are leaving relief unclaimed. If you already complete a tax return, it is worth reviewing your donations before filing. Timing can matter HMRC also allows Gift Aid donations made in the current tax year to be treated as if they were made in the previous tax year, provided the claim is made through your tax return before the filing deadline. That can help where: You paid higher-rate tax in the previous year but not the current one You want relief earlier Gift Aid and adjusted net income Gift Aid can also affect adjusted net income calculations. HMRC’s guidance confirms that Gift Aid donations reduce adjusted net income by the grossed-up amount. In practice: Every £1 donated reduces adjusted net income by £1.25 This matters because adjusted net income is used when calculating: The Personal Allowance taper The High Income Child Benefit Charge For the 2026/27 tax year : The Personal Allowance remains £12,570 The taper begins once income exceeds £100,000 The allowance reduces by £1 for every £2 of income above that threshold. For taxpayers in England, Wales and Northern Ireland, this creates an effective 60% marginal tax rate between £100,000 and £125,140 . A Gift Aid donation can therefore do more than support a charity — it can help restore lost Personal Allowance. For example: An £800 Gift Aid donation becomes £1,000 gross Adjusted net income reduces by £1,000, not £800 That reduction may help recover part of the Personal Allowance as well as generating higher-rate Gift Aid relief. Payroll Giving If your employer or pension provider offers Payroll Giving, this can be a very efficient option for regular donations. Under Payroll Giving: Donations are taken before Income Tax is deducted National Insurance still applies Income Tax relief is applied immediately For most UK taxpayers, donating £1 through Payroll Giving costs: 80p for a basic-rate taxpayer 60p for a higher-rate taxpayer 55p for an additional-rate taxpayer Scottish taxpayers have different rates because Scottish Income Tax bands differ. Payroll Giving is often attractive because: Relief is immediate There is less admin Donations do not need separate tax return claims However, it depends on your employer or pension provider offering a scheme. Gifts of shares, land and property Cash donations are not the only option. In some situations, gifting shares, land or property directly to charity can be significantly more tax-efficient. If you donate qualifying investments or property: You may receive Income Tax relief You usually avoid Capital Gains Tax on the disposal That can be more efficient than selling the asset first and donating cash afterwards. HMRC’s guidance says Income Tax relief is generally based on: The market value of the asset at the time of the gift Plus incidental costs such as broker fees or legal fees Less any benefit received Because these rules are more technical, record-keeping is important. Charitable gifts in your will Charitable giving can also play a role in estate planning. A charitable gift left in a will is exempt from Inheritance Tax because it is deducted from the estate before tax is calculated. There can also be an additional benefit: If at least 10% of your net estate is left to charity, the Inheritance Tax rate may reduce from 40% to 36% For the 2026/27 tax year : The nil-rate band remains £325,000 The residence nil-rate band remains £175,000 These thresholds are frozen until 5 April 2031 For some estates, the reduced tax rate offsets more of the charitable gift than people expect. Common mistakes Some of the most common issues include: Assuming Gift Aid is the end of the process Using Gift Aid without paying enough qualifying tax Ignoring non-cash giving options Claiming relief for organisations that do not qualify Since April 2024, UK charitable tax reliefs generally apply only to qualifying UK charities and UK Community Amateur Sports Clubs (CASCs). Choosing the right route The right option depends on what you are giving and what you want to achieve. For one-off cash donations, Gift Aid is usually the starting point For regular donations from salary or pension income, Payroll Giving may work better For investments or property standing at a gain, direct gifting may be more tax-efficient For estate planning, charitable legacies can reduce Inheritance Tax exposure The key point is that charitable tax relief is broader than many people realise. Gift Aid is only one part of the picture. Before the end of a tax year, it is worth reviewing your donations, checking whether all Gift Aid claims are valid, and making sure any higher-rate relief has not been missed. If you are considering larger gifts involving shares, property or estate planning, it is usually worth getting advice before acting. If you would like tailored advice around charitable giving and tax reliefs , I’m always happy to have a straightforward conversation.
A new report from the Institute for Fiscal Studies has taken a fresh look at the Government’s Help to Buy scheme and concluded that it largely benefited higher earners rather than significantly improving social mobility. The scheme was introduced in England in 2013 with the aim of helping first-time buyers who did not have financial support from family or friends. It worked through two main measures: a mortgage guarantee scheme allowing buyers to purchase with a 5% deposit an equity loan scheme offering a Government-backed loan of up to 20% on new-build properties, rising to 40% in London for part of the scheme At its peak in 2014/15, around one in five first-time buyer purchases in England were supported through Help to Buy. What the report found According to the IFS, the scheme made only a limited difference to overall housing affordability and had relatively little impact on social mobility. One of the main issues highlighted was that the equity loan scheme applied only to new-build homes. Because new-build supply is limited in many parts of the country, particularly in London and the South East, access to the scheme was uneven. Buyers in lower-cost regions were often more able to benefit, and these areas also tended to have higher average incomes relative to local house prices. The report also noted that many buyers were already close to normal mortgage lending limits before using the scheme. In some cases, additional financial help from family was still needed at the last minute. The wider debate Critics of Help to Buy have long argued that the scheme may have pushed house prices higher by increasing buyers’ purchasing power without significantly increasing supply. Supporters, including James Cleverly, continue to argue that it helped thousands of people onto the property ladder while supporting housebuilding activity. As with many housing policies, the reality is probably somewhere in the middle. Where the scheme stands now The equity loan scheme has now closed to new applicants in both England and Scotland, with Wales expected to follow. The mortgage guarantee scheme, however, remains available across the UK. A practical view For many people, affordability remains the biggest challenge when buying a home. Schemes like Help to Buy can improve access in the short term, but they do not necessarily solve the wider issue of housing costs increasing faster than incomes. The report is another reminder that borrowing capacity, deposits and affordability are all closely linked - particularly while interest rates remain relatively high. Final thought Help to Buy clearly supported a large number of purchases over the years, but the latest analysis suggests the long-term impact may have been more limited than originally hoped. For anyone considering buying, moving or reviewing their finances, understanding affordability properly remains far more important than relying on support schemes alone. If you’d like to talk through your finances or longer-term planning, feel free to get in touch.
UK consumers are starting to cut back on travel spending, with the latest figures suggesting households are becoming more cautious about higher discretionary costs. New data from Barclays shows overall card spending rose by just 0.9% year on year in March , slightly down from 1% in February . Within that, travel spending fell by 3.3% , marking the first decline seen since March 2021 . Overseas travel starting to slow The figures suggest many households are either delaying trips abroad or opting for UK-based breaks instead. Spending fell across several travel-related categories, including: travel agents airlines public transport At the same time, hotel and accommodation spending increased slightly by 1.2% , helped by more domestic bookings over the Easter period. Cost pressures still shaping behaviour Wider economic uncertainty continues to affect spending habits. Ongoing tensions in the Middle East have added further concern around energy prices and household costs. Research linked to the Barclays figures found that around one in seven adults have delayed major purchases or focused more on saving because of concerns about rising energy bills. Although the UK energy price cap fell by 7% in April , forecasts suggest it could increase again in July due to higher wholesale energy prices. Essential spending rising again Essential spending increased modestly overall by 0.5% . Fuel spending rose by 1.6% , marking the first increase in more than a year, largely driven by higher oil prices. Discretionary spending growth also slowed to 1.1% , although spending on clothing and entertainment remained relatively resilient. Confidence remains mixed One of the more interesting parts of the data is the contrast in confidence levels. Most people still feel relatively secure about their own household finances, but confidence in the wider UK and global economy has weakened. At the same time, retail sales remained strong overall, increasing by 3.6% year on year , helped by higher food spending. A practical view None of this points to a sudden collapse in spending, but it does suggest households are becoming more selective. Travel is often one of the first areas where people pause or cut back when costs feel uncertain, particularly when energy prices and inflation risks remain in the background. For businesses, this matters because changes in consumer confidence tend to feed through gradually rather than all at once. Final thought The overall picture is still mixed. People are continuing to spend, but there are growing signs that households are becoming more cautious about larger or less essential purchases. As costs, inflation and global uncertainty continue to shift, confidence is likely to remain sensitive over the coming months. If you’d like to talk through your finances or wider business planning, feel free to get in touch.
Pay growth slowing – what it means for businesses There are further signs that wage growth in the UK is starting to ease. The latest figures from the Office for National Statistics show that average earnings (excluding bonuses) rose by 3.8% in the three months to January , down from 4.2% in the previous period . That makes it the slowest rate of pay growth in more than five years . Although growth is slowing, wages are still increasing slightly faster than inflation, which stood at 3% in January . The wider labour market The overall labour market remains relatively stable. Unemployment is at 5.2% , close to a five-year high The number of people on payrolls increased by around 20,000 in February , bringing the total to 30.3 million So while there are signs of softening, it’s not a sharp shift. Public vs private sector pay One area where the difference is more noticeable is between sectors. Public sector pay growth: 5.9% Private sector pay growth: 3.3% This gap has been a consistent theme, and it continues to affect recruitment and retention in some industries. Hiring and vacancies Job vacancies have remained broadly steady. Early estimates suggest a small decline of 6,000 roles , leaving around 721,000 vacancies in the three months to February. In practice, that points to a labour market that is cooling slightly rather than contracting. What this means for interest rates These figures come just ahead of the next decision from the Bank of England. There had been some expectation of a rate cut, but that now looks less likely. Rising fuel and energy costs - linked to ongoing tensions in the Middle East - have increased the risk of inflation picking up again. That makes it more likely that borrowing costs will be held steady for now. A practical view For businesses, this creates a slightly mixed picture. On one hand, slower wage growth can ease some pressure on costs. On the other hand, inflation risks and interest rates remaining higher for longer continue to affect planning and investment decisions. It’s not a dramatic shift - but it’s another sign that conditions are changing gradually rather than quickly. Final thought The key takeaway is that while pay growth is slowing, the wider environment is still uncertain. Costs, wages and borrowing conditions are all moving at the same time, just in different directions. For most businesses, that makes it more important to keep a close eye on margins, staffing costs and forward planning over the coming months. If you’d like to talk through how this might affect your business, feel free to get in touch.
SPOTLIGHT ON: Pension allowances Practical steps to keep pension planning on track Pensions are still one of the most tax-efficient ways to save for the long term. They can reduce taxable income, support how business owners take money out of their company, and build retirement funds in a structured way. Where things tend to go wrong is not the idea of contributing - it’s contributing without checking the rules first. That’s when a sensible contribution can lead to an unexpected tax charge. The good news is that most issues come from a fairly small number of areas: the annual allowance, tapering for higher earners, the money purchase annual allowance (MPAA), and missed carry forward checks. For the 2025/26 tax year , the standard annual allowance is £60,000 , but in some cases it can fall to £10,000 . This guide looks at the key checks to make before contributing and where problems usually arise. Start with the annual allowance For most people, the starting point is the standard annual allowance: £60,000 for 2025/26 Applies across all pensions combined , not each one separately Going over it can trigger a tax charge if there isn’t enough carry forward available One of the common misunderstandings is what counts towards that limit. It’s not just what you personally pay in. It can include: Personal contributions Employer contributions Contributions made by others Pension growth under defined benefit schemes This is why people get caught out - the figure used for tax purposes is often higher than expected. Tax relief isn’t the same as the allowance Another area that causes confusion is the difference between tax relief and the annual allowance. In simple terms: The annual allowance is the limit before a potential tax charge Tax relief on personal contributions is usually limited to 100% of your earnings Employer contributions follow different rules This is particularly relevant for directors and business owners. For example, someone with a low salary might assume they can’t contribute much personally, but employer contributions could still be an efficient route. Equally, staying within personal earnings limits doesn’t guarantee you’re within the annual allowance once everything is added together. Check if tapering applies For higher earners, the full £60,000 allowance doesn’t always apply. Tapering can reduce it where: Threshold income exceeds £200,000 Adjusted income exceeds £260,000 If tapering applies: The allowance reduces by £1 for every £2 over £260,000 It can fall to a minimum of £10,000 This is a common source of surprise tax bills, especially where income fluctuates - for example through dividends, bonuses or business profits. Watch for the MPAA The money purchase annual allowance (MPAA) is another key area. For 2025/26, it is £10,000 and can apply if you’ve flexibly accessed a pension . This often catches people who: Take taxable income from a pension Assume it’s a one-off decision Then later want to contribute again Once triggered, it can significantly limit future contributions. Don’t overlook carry forward Carry forward can make a big difference. HMRC allows unused allowance from the previous three tax years to be carried forward, subject to conditions. This is particularly useful where: Profits increase A business wants to make a larger contribution Retirement planning has been delayed But it’s also an area where assumptions cause problems. You need to check: Whether you were part of a pension scheme in those years What your actual allowance was Whether tapering applied How much was already used It works well - but only if the numbers are correct. Where issues usually arise Most pension tax charges aren’t caused by pensions themselves, but by lack of review. Common causes include: Assuming the allowance is always £60,000 Missing tapering for higher earners Forgetting the MPAA applies Ignoring employer contributions Relying on carry forward without checking Making last-minute contributions without reviewing income Most of these are avoidable with a simple annual check. Income changes make this more important Planning becomes more sensitive where income varies. Extra care is usually needed if you: Take a mix of salary and dividends Run your own business Receive bonuses or irregular income Are approaching retirement Have started taking pension withdrawals In these cases, it’s better to review contributions during the tax year rather than relying on assumptions. A simple review process A short review before making contributions can prevent most issues. This should cover: Total pension input for the year Whether the full allowance applies Whether tapering is relevant Whether the MPAA applies Available carry forward Whether personal or employer contributions are more efficient It doesn’t need to be complicated - but it does need to happen before money goes in. Other limits to keep in mind The annual allowance is the main consideration, but there are other pension limits worth noting. For 2025/26 : Lump sum allowance: £268,275 Lump sum and death benefit allowance: £1,073,100 These are less likely to create immediate issues but still matter for long-term planning. Final thought Pensions remain a strong planning tool, but the rules aren’t always as simple as the headline figures suggest. Most problems aren’t about contributing too much - they’re about not checking first. A short review each year is usually enough to avoid surprises. If income is changing or you’ve started accessing pensions, that review becomes more important. If you’d like help checking your position before making contributions, feel free to get in touch.
The Government has announced new proposals aimed at increasing youth employment, with financial incentives for businesses that take on younger workers. At the centre of the plan is a £1bn funding package , with a target of creating around 200,000 jobs . For employers, the headline point is straightforward: there may soon be direct financial support for hiring . What’s being proposed Under the proposals, businesses could receive: £3,000 for each person aged 18 to 24 they employ, where that individual has been out of work and actively seeking employment for at least six months £2,000 for each new apprentice taken on by small and medium-sized businesses The Government estimates that around 60,000 young people could benefit directly from these measures. Alongside this, there are plans to expand the existing jobs guarantee scheme . At the moment, individuals aged 18 to 21 who have been on Universal Credit and looking for work for 18 months are guaranteed a six-month job placement. The new proposals would extend that eligibility up to age 24. What this means in practice For businesses, this is less about policy and more about opportunity. If you are already considering hiring (particularly at entry level) these grants could help reduce the initial cost and risk. For some businesses, that may make the difference between delaying a hire and bringing someone in sooner. Apprenticeships are also clearly part of the direction of travel, with additional support aimed at encouraging SMEs to invest in training and development. The wider context These proposals sit alongside broader employment reforms currently being considered. The Government’s Employment Rights legislation includes plans to strengthen worker protections, including reducing the qualifying period for unfair dismissal claims from two years to six months. Taken together, the direction is fairly clear: More support to get people into work More structure around employment rights once they are there A practical view For many businesses, recruitment decisions come down to timing, cost and confidence. Grants like this don’t change the fundamentals, but they can make hiring more accessible — particularly where you are looking to grow steadily rather than quickly. If you are planning to recruit over the next 12–18 months, it’s worth keeping an eye on how these proposals develop and whether they apply to your situation. Final thought The key point is that these are still proposals, but they give a good indication of where policy is heading. For businesses open to bringing in younger staff or apprentices, there may be practical support available — and it’s worth understanding how that fits into your plans. If you’d like to talk through how hiring decisions impact your wider finances, feel free to get in touch.
SPOTLIGHT ON: MTD for income tax: Your April 2026 checklist Practical steps to get ready for the new reporting rules. Making Tax Digital for income tax (MTD IT) starts from 6 April 2026 for sole traders and landlords with qualifying income over £50,000 . For many businesses and property owners, the change is less about extra tax and more about changing how records are kept and how income is reported to HMRC through the year. HMRC says those in scope will need to keep digital records, send quarterly updates through compatible software, and then complete a year-end process through that software. HMRC has also confirmed that this rollout will widen in later phases, to qualifying income over £30,000 from 6 April 2027 and over £20,000 from 6 April 2028 . The main risk is leaving preparation too late. Businesses that already keep clean digital records and reconcile income regularly are likely to find the transition manageable. Those still relying on paper files, spreadsheets with manual rekeying or a year-end tidy-up may find April 2026 more disruptive than expected. This guide sets out who needs to act now, what the new process looks like, and the practical checks worth making before the start date. Check first whether you are in scope The April 2026 start date does not apply to everyone in self assessment. It applies first to sole traders and landlords whose total qualifying income from self-employment and property was more than £50,000 in the 2024 to 2025 tax year . HMRC’s eligibility guidance says the test is based on qualifying income from those sources, not total income from all sources. That means salaries, dividends and savings income do not count towards the threshold for deciding whether April 2026 applies, although those figures may still be relevant later in the tax return process. Qualifying income can include: income from self-employment income from UK property income from foreign property income from more than one business or property source combined. HMRC also says income from ceased self-employment or property sources can still count towards qualifying income for the threshold test if it appears on the relevant tax return. That is worth checking where a business has changed, split or ceased activity during the year. Be clear on who is not starting in April 2026 A lot of unnecessary concern has come from people assuming MTD IT will apply to every taxpayer from April 2026. It will not. As things stand: sole traders and landlords with qualifying income over £50,000 start from 6 April 2026 those over £30,000 start from 6 April 2027 the government has set out plans for those over £20,000 to start from 6 April 2028 limited companies are not within this April 2026 MTD IT rollout partnerships are not part of the first phase starting in April 2026. That makes this a narrower change than some headlines suggest, but it is still significant for many landlords, sole traders and owner-managed businesses operating outside a company. Thresholds are for gross income, not net. Understand what the new process actually involves MTD IT is not just a digital version of the current self assessment return. HMRC says the process has three main parts. You will need to: create, store and correct digital records of self-employment and property income and expenses send quarterly updates to HMRC using compatible software submit a year-end tax return process , including any other income and gains, and pay tax due by 31 January following the end of the tax year. HMRC has described the quarterly submissions as light-touch quarterly updates rather than extra tax returns. That wording matters, because the update is a summary of digital records for the period, not a full tax calculation each quarter. Get familiar with the quarterly deadlines For many clients, the biggest change in habit will be the reporting rhythm. HMRC’s current guidance says the quarterly update deadlines are: 7 August 7 November 7 February 7 May. That means businesses in scope from 6 April 2026 will move away from a single annual reporting mindset for business and property income. The work will need to be spread through the year, even though the tax payment timetable remains separate. This is one reason April 2026 preparation matters. The businesses that struggle are likely to be those still treating bookkeeping as a once-a-year job. Know what records must be kept digitally HMRC’s digital record guidance is fairly direct. Businesses within MTD IT must create and store digital records of self-employment and property income and expenses. For each item of income or expense, the record needs to include: the amount the date the category of income or expense. HMRC says MTD IT uses the same categories of income and expenses as self assessment. For self-employment, that includes items such as sales, takings, fees, stock costs, travel, office costs and financial costs. For property, it includes rent and property expenses such as repairs, maintenance and services. In practice, the key point is that a rough spreadsheet total or a box of invoices handed over after the year end is no longer the standard MTD is built around. The system expects business and property records to be digital and kept up to date. Check whether your software is ready Compatible software is central to the new regime. HMRC says those in scope will need software that works with MTD IT to keep records, send quarterly updates and complete the year-end submission. There are both full bookkeeping products and bridging-style options on HMRC’s recognised software list, depending on how a business prefers to work. Before April 2026, review whether your current set-up can handle: digital record-keeping for all business and property income streams quarterly updates to HMRC year-end submission through the same or linked software inclusion of other sources of income and gains at the end of the tax year, where relevant. A business may not need the most expensive system on the market, but it does need one that matches how the records are kept in real life. Review how many income streams need tracking One of the more practical issues is that many people affected by MTD do not have just one tidy source of income. A taxpayer may have: one or more self-employments UK rental income foreign property income ceased sources still relevant to the threshold test other personal income that still needs to be included at the year-end stage. That means the bookkeeping question is not only “Do I have software?” but also “Does my set-up properly separate and capture each source?” This matters because weak source separation creates avoidable problems later, especially where one person has both trading and property income. Do not assume the old annual tidy-up will still work Under the old habit pattern, many sole traders and landlords could leave bookkeeping in poor shape for months and still pull together a tax return before 31 January. MTD IT is designed to change that. A sensible shift now is to move towards: monthly bookkeeping monthly or quarterly reconciliations clearer digital storage of invoices and expense evidence regular review of business and property categories fewer year-end adjustments caused by incomplete records. This is not only about compliance. More regular records usually make it easier to track profit, cashflow and tax exposure through the year. Understand the first-year penalty position properly One of the most useful current easements is that HMRC says it will not apply penalty points for late quarterly updates in the first mandatory year, 2026 to 2027 , for those required to join from April 2026. However, that does not mean there is no consequence to poor compliance. HMRC also says: digital records still need to be kept quarterly updates still need to be sent before the tax return can be completed penalties can still apply for late tax returns penalties and interest can still apply if tax is paid late. So the easement is helpful, but it is not a reason to delay preparation. It mainly gives affected taxpayers and agents more room to settle into the quarterly cycle without immediate late-update penalty points. Check whether an exemption may apply Not everyone who would otherwise fall within the thresholds has to use MTD IT. HMRC’s exemption guidance says some people are automatically exempt, including: those with qualifying income of £20,000 or less those without a national insurance number trustees and personal representatives, in relation to those roles certain Lloyd’s members some people who are not physically or mentally capable of using the system, depending on the conditions met. HMRC also says people may be exempt if they are digitally excluded , meaning it is not reasonable for them to use compatible software to keep records or submit them. Agents can apply on behalf of clients in that position. HMRC has said those clients should still be prepared for MTD while an exemption application is being considered, in case it is refused. That makes exemption an issue to review early rather than close to the deadline. Prepare for the year-end step, not just the quarterly updates Quarterly updates are only part of the process. HMRC says that before the final year-end submission is completed, the software will need to include other sources of income and gains where relevant. The final declaration deadline remains 31 January after the end of the tax year. HMRC’s developer guidance states that the final declaration can be made from 6 April after the year end, with a deadline of 31 January the following year. This matters because MTD IT does not remove the need to bring together the wider tax picture. It changes the route and timing for business and property records, but the end-of-year completion step still matters. If you are below the threshold, do not ignore this completely Businesses and landlords below the April 2026 threshold may still want to act early. HMRC allows voluntary sign-up in some cases, and the wider rollout means many taxpayers who are not affected in 2026 may still be affected in 2027 or 2028. HMRC’s current sign-up guidance says someone who will be required from a later date can choose to sign up voluntarily now for the current tax year, provided they are eligible and use compatible software. For some, the best use of 2025 to 2026 is not early enrolment but process improvement, so it is a good time to: clean up records move to compatible software separate business and personal transactions properly improve source document storage get used to quarterly bookkeeping reviews. A practical April 2026 checklist Use this checklist to see what needs doing now. Confirm whether April 2026 applies Check your 2024 to 2025 qualifying income from self-employment and property. If the total is over £50,000 , assume April 2026 is live unless an exemption applies. List all relevant income sources Separate each self-employment. Separate UK and foreign property income where relevant. Identify any ceased sources that still affect the threshold calculation. Review digital records Can you record income and expenses digitally by amount, date and category? Are records up to date enough to support quarterly updates? Check software Confirm whether your current software is compatible with MTD IT. If not, decide whether to move to bookkeeping software or a bridging option. Set a quarterly timetable Build internal deadlines ahead of 7 August, 7 November, 7 February and 7 May . Do not rely on the first-year easement as a substitute for a process. Review exemptions early Check digital exclusion or automatic exemption grounds where relevant. If applying, do it early and keep preparing in parallel. Prepare for the year-end stage too Make sure the year-end process will still capture other income and gains, not just business and property summaries. How I can help The businesses most likely to handle MTD well are the ones that treat it as a records and process project, not just a filing deadline. The quickest wins usually come from confirming whether the threshold applies, cleaning up income sources, choosing the right software and setting a workable quarterly routine. I can help you: confirm whether April 2026 applies based on your qualifying income review whether your records meet HMRC’s digital requirements choose or assess software for quarterly reporting separate self-employment and property records properly prepare an internal timetable for quarterly updates and the year-end submission review whether an exemption may apply. Looking forward MTD IT is now close enough that affected businesses should treat it as a live change, not a future one. HMRC is already urging those in scope to act, and the move to quarterly digital reporting will be much easier where the groundwork is done before 6 April 2026. HMRC said on 5 February 2026 that 864,000 sole traders and landlords face the new rules from April 2026, which gives a sense of how many taxpayers are now in the countdown phase. The practical message is simple: confirm whether you are in scope, get the records into good shape, check the software, and build a reporting routine before the first quarterly deadline arrives. Need help with MTD? I can assist.
Mortgage rates have moved up quickly in recent weeks, and it’s starting to show in the numbers. New data suggests a typical borrower is now paying around £788 more per year . The figures, compiled by Moneyfacts, are based on a £250,000 mortgage over 25 years , with the average two-year fixed rate now at 5.28% . What’s changed The shift has been fairly rapid. Since late February, lenders have been reacting to increased global uncertainty by adjusting rates and pulling back some of their most competitive deals. Only a few weeks ago, fixed-rate mortgages below 4% were widely available . Those have now largely disappeared. Several major lenders, including Barclays, HSBC, NatWest, Nationwide and Santander, have withdrawn those lower-rate products altogether. How far rates have moved Average mortgage rates have climbed in a short space of time: Two-year fixed rates have risen from 4.83% at the start of March to 5.28% Five-year fixed rates have increased from 4.95% to 5.32% For someone taking a five-year deal, that increase works out at around £651 more per year compared with just a couple of weeks ago. Fewer options available It’s not just about higher rates — there are also fewer choices. There are currently 689 fewer mortgage products available than earlier in the month, which reduces flexibility for both buyers and those looking to remortgage. That said, the situation is still less severe than what we saw after the September 2022 mini-Budget , when roughly a quarter of all mortgage deals were withdrawn. What this means for borrowers If you’re already on a fixed-rate mortgage, nothing changes immediately. You’re protected until your current deal ends. The pressure tends to come when you’re approaching renewal. With rates moving quickly and lenders adjusting their products in response to wider economic conditions, timing and planning start to matter more. If you’re due to remortgage in the next 6–12 months, it’s worth looking at your options earlier rather than later. A practical approach Mortgage rates are influenced by factors outside anyone’s control, global events, inflation expectations and decisions by the Bank of England . What you can control is preparation. Understanding what your payments might look like at different rates, and how that fits alongside your wider finances, makes it easier to plan and avoid surprises. Final thought The key takeaway is that the mortgage market can move quickly, even over a matter of weeks. If you’re approaching a renewal or considering borrowing, it’s worth taking a bit of time to understand where you stand rather than relying on assumptions based on older rates. If you’d like help looking at how this might affect your overall finances, feel free to get in touch.
Where profit quietly disappears in growing Ltd companies Turnover is up. Sales look healthy. The business feels busy. But profit doesn’t quite reflect the effort. This is a common pattern in growing owner-managed companies. Nothing dramatic has gone wrong. There’s no obvious issue. But margins feel tighter than they should. Profit rarely disappears in one place In most cases, profit doesn’t drop because of a single event. It leaks. And those leaks are often easy to miss when the business is growing. Where it tends to go There are a few patterns that come up regularly: Overheads creeping up quietly Software subscriptions, small hires, additional services — each one makes sense individually. Over time, they permanently increase the cost base. Pricing that hasn’t kept up with complexity As the business grows, the work often becomes more demanding. If pricing doesn’t move with it, margins reduce. Revenue growth masking inefficiency When sales are increasing, inefficiencies are easy to ignore. When growth slows, they become much more visible. Small write-offs or slow-moving work Nothing dramatic — just gradual erosion over time. Director drawings without forward visibility Not wrong, but if they aren’t planned alongside cashflow, they can create pressure later. None of these are signs of failure. They’re usually just signs of a business that has grown without regular commercial review. What growing businesses usually need At this stage, most businesses don’t need major change. They need better visibility. Typically, that means: A clear view of gross margin Tracking overhead trends over time Regular cashflow forecasting Stepping back quarterly to review what the numbers are actually saying The changes themselves are often small. But making them early is far easier than correcting things later. Looking beneath the surface If profit feels tighter than turnover suggests, it’s usually worth looking a bit deeper. Not to find problems, but to understand what’s actually happening underneath the surface. Because in most cases, the issue isn’t dramatic. It’s just been building quietly. Part of a bigger picture This is the third post in a short series on how growing businesses interact with their numbers. If you haven’t read the earlier ones, you may also find these useful: The Signs You’ve Outgrown Your Accountant If Your Management Accounts Don’t Change Decisions, They’re Not Working Together, they look at how financial information should evolve as a business grows, and how small changes in visibility can lead to better decisions. If any of this sounds familiar, I’m always happy to have a straightforward conversation about how your numbers are behaving and whether they’re giving you the visibility you need.
The Government has announced a £50m support package for low-income and vulnerable households that rely on heating oil, as prices have risen sharply following the conflict in the Middle East. Kerosene, which is used in heating oil systems, has increased more quickly than petrol and mains gas in recent weeks. Unlike gas and electricity, heating oil is not covered by the energy price cap. That means households who are off the gas grid are more exposed to sudden price changes, often having to pay large upfront amounts to refill their tanks. How the support will be distributed The funding will be distributed through local councils from 1 April , using the new Crisis and Resilience Fund (CRF) . The allocation has been split based on regional demand: £27m for England £17m for Northern Ireland £4.6m for Scotland £3.8m for Wales Northern Ireland is expected to be most affected, with up to 60% of homes relying on heating oil . Why this matters One of the main challenges with heating oil is how it’s paid for. Unlike monthly direct debits for gas and electricity, heating oil often requires lump sum payments , which can put pressure on household finances, particularly when prices rise quickly. Ministers have acknowledged that this creates additional financial strain for vulnerable households trying to maintain heating and hot water. Wider review of the heating oil market Alongside the support package, the Government has announced a broader review of the heating oil market. This includes: Looking at introducing sector-wide regulation for the first time Improving consumer protections Working with suppliers to improve service standards The Competition and Markets Authority (CMA) is also investigating the market to assess whether pricing is fair. Further proposals include appointing a formal regulator — potentially Ofgem — and introducing an ombudsman under the proposed Energy Independence Bill . Final thoughts For households affected, this support may help in the short term. Longer term, the focus is likely to shift towards how the market is regulated and how exposed off-grid households remain to price volatility. As with most cost pressures, the key is understanding how rising costs affect your overall finances and planning accordingly. If you’re reviewing your household or business finances in light of rising costs, I’m always happy to chat.
What online sellers must record and report Online selling can scale quickly. That’s great for revenue, but it puts pressure on record-keeping, VAT decisions and how you report to HMRC. Unlike a traditional business with one sales ledger and one bank account, online selling usually involves multiple moving parts: your website or marketplace, a payment processor, fulfilment providers and often advertising platforms driving demand. Each of these produces its own reports, timelines and deductions. They don’t always line up neatly with what actually lands in your bank. At the same time, visibility has increased. Digital platforms now report seller income and activity to HMRC each year. That means HMRC can compare platform data against your tax returns, VAT submissions and digital records. Selling online doesn’t create a problem by default, but it does mean inconsistencies show up more easily. Why this matters more than it used to Online retail remains a significant part of the UK economy. The Office for National Statistics reported that 28.3% of retail spending was online in December 2025 , up from 28.0% in November , with online sales values 11.1% higher than December 2024 . For businesses, that growth usually means: More transactions (and more refunds and chargebacks) More intermediaries (platforms, processors, fulfilment providers) More cross-border sales affecting VAT More third-party data that HMRC can cross-check The goal is simple: keep records clean and consistent so you can run the business properly and support your tax position if needed. What counts as “selling online”? From a compliance point of view, it doesn’t matter whether you sell: Through your own website (e.g. Shopify) Through marketplaces like Amazon, eBay or Etsy Through social platforms Via payment systems like PayPal or Stripe What changes is where the data sits, and whether the platform has reporting obligations to HMRC. The core principle Tax is based on profit. Sales income (turnover), less allowable costs, equals taxable profit. But HMRC expects evidence. That means your records need to show: What you sold When you sold it What you were paid (and what was deducted) What it cost you Any VAT charged or reclaimed How your tax figures were calculated The key point: you need to record gross activity — not just what hits your bank. What to keep 1. Sales records (gross, not payouts) For each sales channel, keep: Order dates and numbers Customer location Items, quantities and prices Delivery charges Discounts and vouchers Refunds and cancellations VAT charged Common issue: treating payouts as sales. Payouts are usually sales minus fees and refunds , so relying on them can understate turnover. 2. Platform reports Keep: Monthly statements Transaction-level exports Settlement reports VAT invoices for fees Save these regularly — platform data can change after refunds or disputes. 3. Payment processor records Include: Payout reports Chargebacks and disputes Fees and currency charges Any reserves held 4. Cost evidence Keep invoices and receipts for: Stock and imports Shipping and packaging Fulfilment costs Software and subscriptions Advertising Professional services Staff and subcontractors 5. Bank records Alongside statements, keep: Reconciliation schedules Notes for unusual items Separate accounts or clear tracking makes this much easier. 6. Stock records Keep track of: Stock received Inventory movements Returns and write-offs Stock counts This supports both operations and profit accuracy. How long to keep records Self assessment: at least 5 years after the filing deadline VAT: typically 6 years (10 years for OSS/MOSS) Limited companies: generally 6 years from the end of the financial year In practice, many businesses keep six years plus the current year . Platform reporting to HMRC From 1 January 2024 , digital platforms must report seller income and details to HMRC annually. This includes: Name and address Date of birth (for individuals) Tax identifiers (e.g. NI number or company number) There is an exemption for low activity (fewer than 30 sales and under €2,000 - about £1,700). What this means in practice HMRC can see platform-level data Differences between your returns and platform figures may trigger questions Keeping accurate records is more important than ever A simple control: Reconcile platform totals to your accounts regularly. VAT considerations UK threshold For 2025/26, the VAT threshold is £90,000 (rolling 12 months). Common VAT issues Cross-border sales Marketplace VAT rules (especially under £135 consignments) Import VAT documentation Missing paperwork is one of the most common reasons VAT reclaims are challenged. Making Tax Digital (MTD) MTD for VAT All VAT-registered businesses must: Keep digital records Submit VAT returns via compatible software Late submissions now operate under a points-based penalty system . MTD for income tax (from April 2026) Applies to sole traders and landlords with income over £50,000 (2024/25). This means: Quarterly updates Digital record-keeping Even now, it’s worth preparing your systems to handle this. A practical workflow Monthly Import sales and fees Reconcile payouts to bank Check refunds Store invoices and receipts Quarterly Review VAT position Check margins by platform Reconcile platform totals Annually Download full reports Review stock Check VAT position Confirm business details across platforms Common mistakes Mixing personal and business transactions Recording payouts as turnover Missing VAT evidence Ignoring overseas stock rules Not saving data regularly Most issues come from small inconsistencies building up over time. Final thoughts Selling online can look simple from the outside, but the record-keeping behind it rarely is. The biggest risks aren’t usually major errors, they’re small gaps that build over time. Missing a month of fees, recording net instead of gross, or losing track of returns. With the right structure in place, though, it becomes manageable. Clean records don’t just keep HMRC happy — they make the business easier to run.
What happens next if you’re one of them? Around one million taxpayers missed the 31 January deadline for submitting their 2024/25 self-assessment tax return. HMRC data shows just how last-minute things were for many people. More than 27,000 returns were filed in the final hour , with 475,722 submitted on the final day alone . In total, around 11.5 million returns were filed. Even with extended helpline hours and webchat support, a significant number of people still didn’t make the deadline. What happens if you miss it? If you missed the deadline, the first thing to know is that a £100 fixed penalty is applied automatically . This applies even if: You don’t owe any tax You’ve already paid what was due From there, the penalties can increase quickly if the return remains outstanding. How penalties build up If your return is still not submitted: After 3 months: £10 per day (up to £900) After 6 months: £300 or 5% of the tax due (whichever is higher) After 12 months: another £300 or 5% charge On top of that, late payment penalties may apply: 5% of unpaid tax after 30 days Another 5% after 6 months Another 5% after 12 months Interest is also charged on any overdue amounts. Who needs to file a self-assessment return? Self-assessment generally applies if you have income that isn’t taxed automatically through PAYE. That can include: Self-employment income over £1,000 Rental income from property Other untaxed income streams Can penalties be appealed? HMRC has confirmed it will review cases where there is a reasonable excuse for missing the deadline. However, in most cases, the practical advice is: Submit the return as soon as possible Pay any initial penalties promptly Even if you plan to appeal, dealing with it early can prevent further charges from building up. Final thoughts Missing the deadline is more common than people think, but leaving it unresolved is where the real cost starts to build. If you’ve missed the deadline or you’re not sure what to do next, it’s worth getting it sorted sooner rather than later. If you need help with your self-assessment, I’m always happy to have a straightforward conversation.